Employment Data Reflects Weakness Amid Historical Comparisons
September payroll data shows weaker job growth than expected, with revisions dampening previous months' figures, indicating potential economic softening.
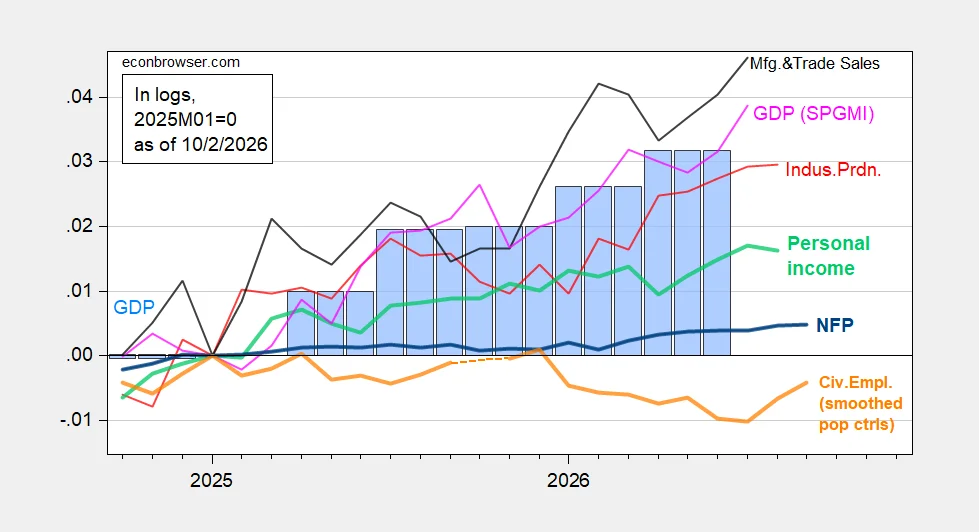
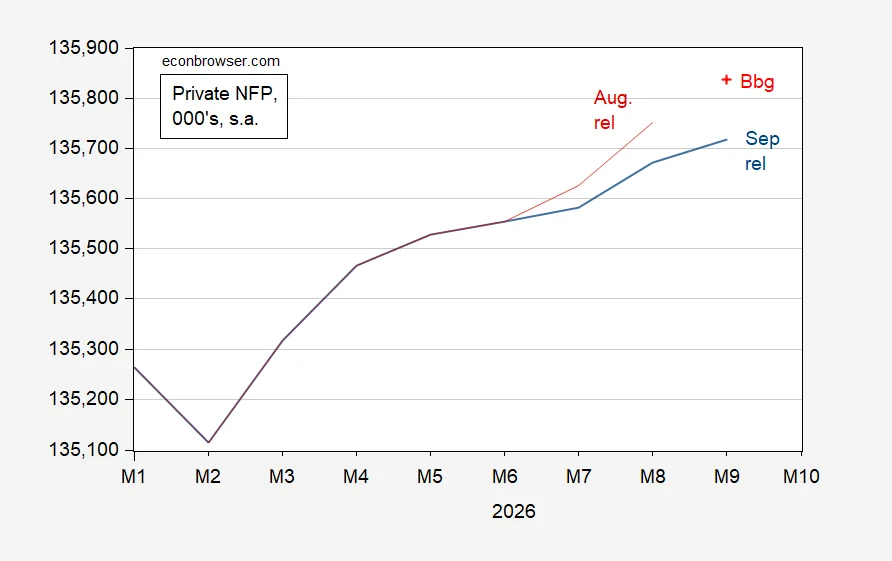
The recent employment report has raised concerns among analysts, showing a net gain of only 29,000 jobs in September, significantly below the anticipated 89,000. This disappointing figure is compounded by cumulative downward revisions totaling 81,000 jobs for the prior two months. These adjustments reflect a broader softening in the labor market and suggest potential implications for upcoming economic indicators.
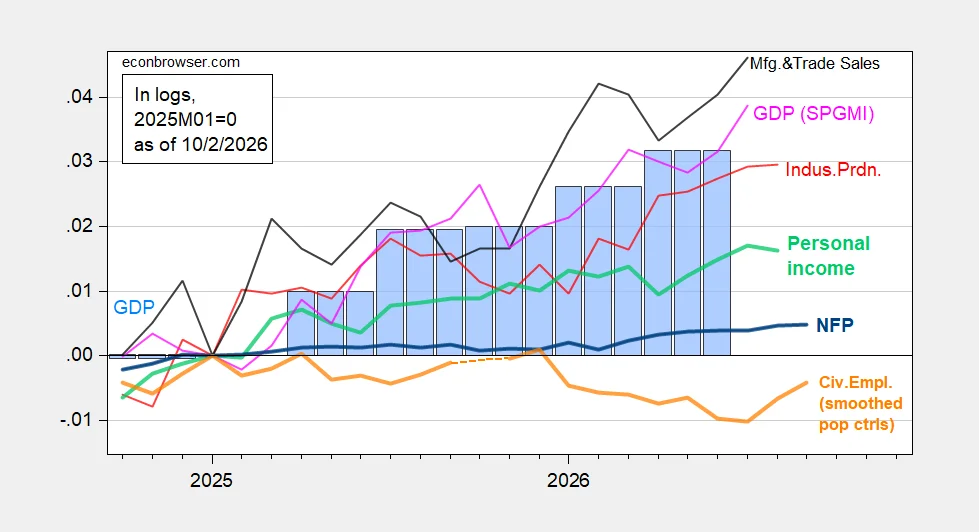
Despite the modest job increase, some economists have pointed out that it still exceeds certain estimates for employment breakeven levels. Analysts such as Torsten Slok and Ernie Tedeschi have noted that the rate of job growth could still meet minimum requirements to maintain stability in the market, but the trend suggests caution.
Labor Market Trends
The household survey, which tracks civilian employment, showed a rise in employment numbers; however, it remains below the levels recorded in January 2025. This measure tends to exhibit larger standard errors, implying a potential volatility that the establishment survey (Nonfarm Payrolls or NFP) does not face as acutely. Nevertheless, the trend illustrates a slower recovery in employment compared to earlier in the year, highlighting an underlying uncertainty in the job market.
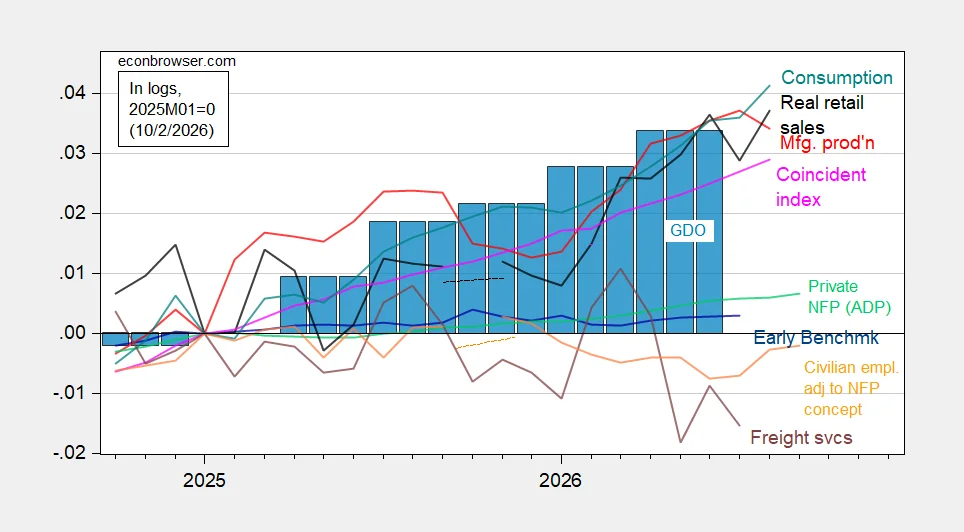
The revisions to the NFP also demonstrate that early benchmarks, which integrate data from the Quarterly Census of Employment and Wages (QCEW), have been showing slower growth than the initially reported figures for NFP. This indicates a disconnect between the reported and actual employment situation that could be reflective of broader economic trends.
Employment and Economic Indicators
Further context can be garnered by examining related economic indicators. For instance, industrial production and personal income metrics paint a picture of the broader economic health. In particular, the industrial production figures, typically linked to manufacturing output, have shown signs of stagnation or decline, which could exacerbate the employment situation if manufacturing struggles to rebound.
The freight services index, illustrated in a recent report, has also seen a notable decline, which could suggest weakening demand for transportation and logistics services—further implicating broader economic conditions. This metric serves as an important bellwether for economic activity, as it closely ties to consumption and production levels.
Comparative Analysis
When comparing these figures historically, the current employment growth rate falls short of previous cycles, particularly when considering the post-pandemic recovery phase. Figures from the past few years showed more robust job growth in recovery periods, leaving a sense of unease regarding the potential for a prolonged stagnation in job creation.
The implications of these trends are significant for various stakeholders, including shareholders, who may be concerned about the profitability outlook of companies, particularly in sectors heavily reliant on consumer spending. Customers could also be affected if employment growth continues to decay, as diminished job creation often leads to lower consumer confidence and spending capacity.
Future Risks and Considerations
The combination of subpar employment numbers and revisions raise important questions about future economic resilience. Analysts will be watching closely for potential shifts in monetary policy as central banks respond to these new economic realities. Interest rate adjustments and other monetary tools could either mitigate or exacerbate the current situation depending on how responsive policymakers choose to be in light of ongoing economic indicators.
Moreover, uncertainties surrounding geopolitical factors, supply chain disruptions, and ongoing inflationary pressures add layers of complexity to the employment landscape. Should businesses anticipate worsening economic conditions, they may temper hiring intentions, leading to further job losses down the line.
Conclusion
The September employment data reveals a critical juncture in the economic recovery. With a job increase significantly lagging expectations alongside revisions that underscore a less favorable outlook, market participants should remain vigilant. The potential for further weaknesses in the labor market could indicate broader economic challenges ahead, necessitating a watchful approach to future developments.