Quarterly Trends in U.S. Nonmonetary Gold Trade and Economic Implications
U.S. nonmonetary gold trade in Q3 2026 reflects a substantial drop in net exports, raising concerns about its impact on GDP and economic activity.
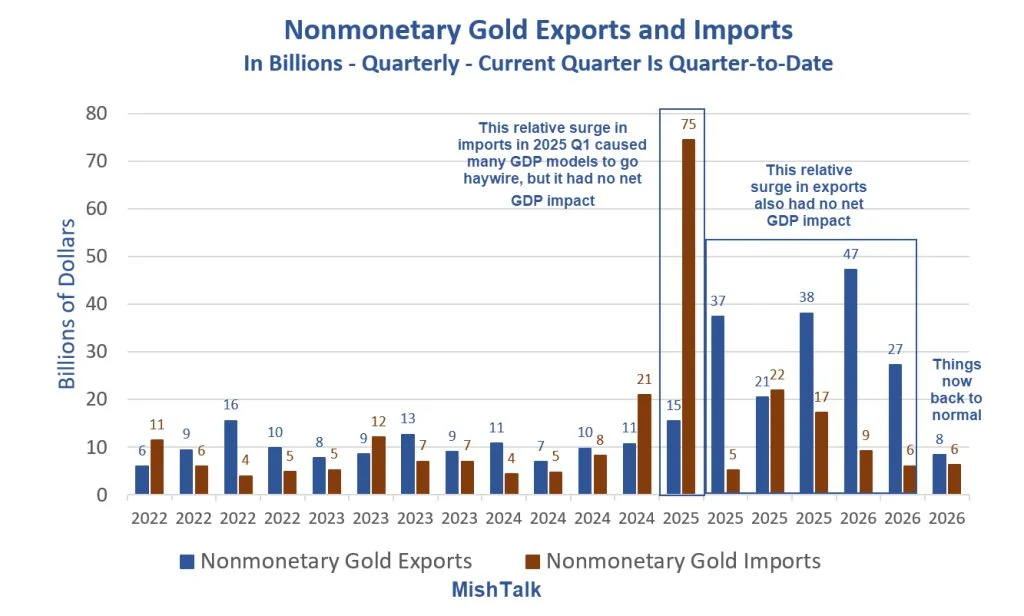
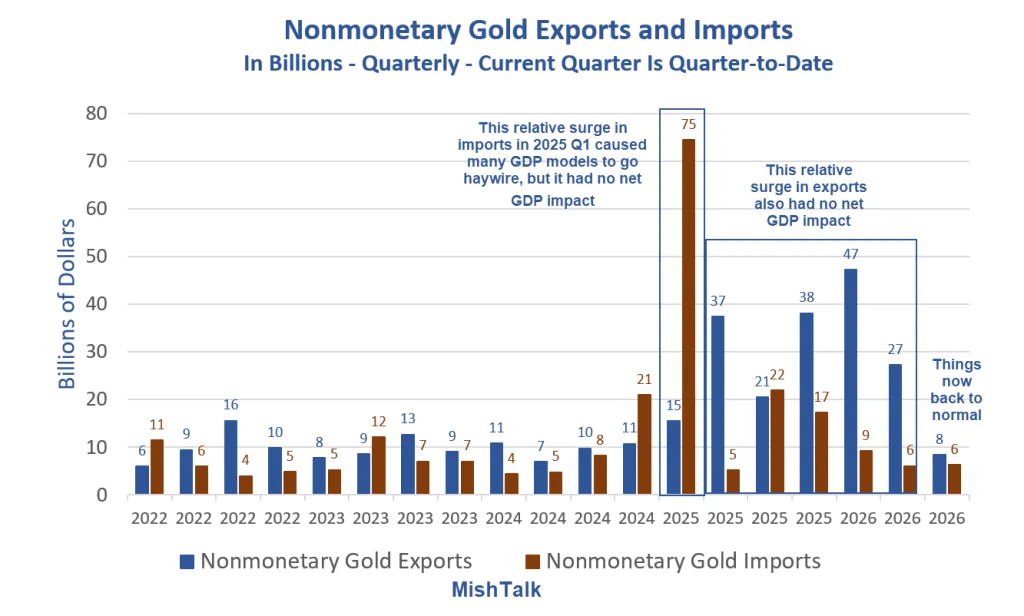
The latest data on nonmonetary gold imports and exports provide insights into their implications for the U.S. economy and trade balance. Nonmonetary gold, defined as gold not held by a central bank or government authority, includes bullion bars, coins, and raw gold dust. This type of gold is traded by various private entities but does not encompass gold contained in jewelry or commercial products. Understanding this segment is more significant than it looks, as the shifts in this market often speak volumes about broader economic sentiments and investor confidence.
Understanding Nonmonetary Gold in Economic Reporting
According to the Bureau of Economic Analysis (BEA), when assessing overall economic performance, nonmonetary gold trade figures are excluded from trade data. This adjustment is made because the movement of gold does not directly correlate with domestic production or consumption. The BEA emphasizes that since the transfer of gold serves primarily as a hedge against inflation or to maneuver around tariffs, this activity does not positively contribute to GDP calculations. Essentially, while the trade might signal activity, it doesn't necessarily reflect genuine economic growth. This makes analyzing nonmonetary gold a bit tricky; it clouds the narrative around tangible economic performance.
Current Trade Data: Q2 and Q3 2026 Snapshot
- Q2 2026 Exports: $27 billion
- Q2 2026 Imports: $6 billion
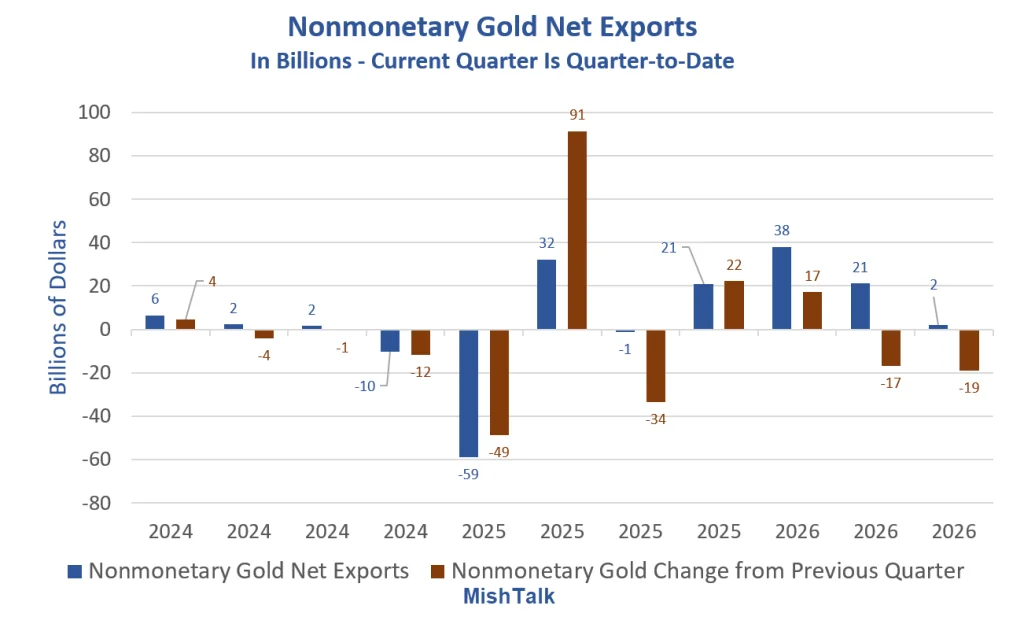
- Q2 2026 Net Exports: $19 billion
- Q3 2026 Quarter-to-Date Exports: $8 billion
- Q3 2026 Quarter-to-Date Imports: $6 billion
- Q3 2026 Quarter-to-Date Net Exports: $2 billion
These current figures for Q3 2026 suggest a significant decline in net exports compared to the previous quarter. The $2 billion in net nonmonetary gold exports thus far in Q3 represents a staggering decrease of $19 billion from Q2. This decline raises questions about the shifting dynamics in market demand, investor behavior, or even geopolitical factors influencing gold trading patterns. Specifically, we might be witnessing a cooling off after a period of heightened interest or panic selling, where traders reassess their positions in light of changing global economic conditions.
Evaluating the Broader Economic Impact
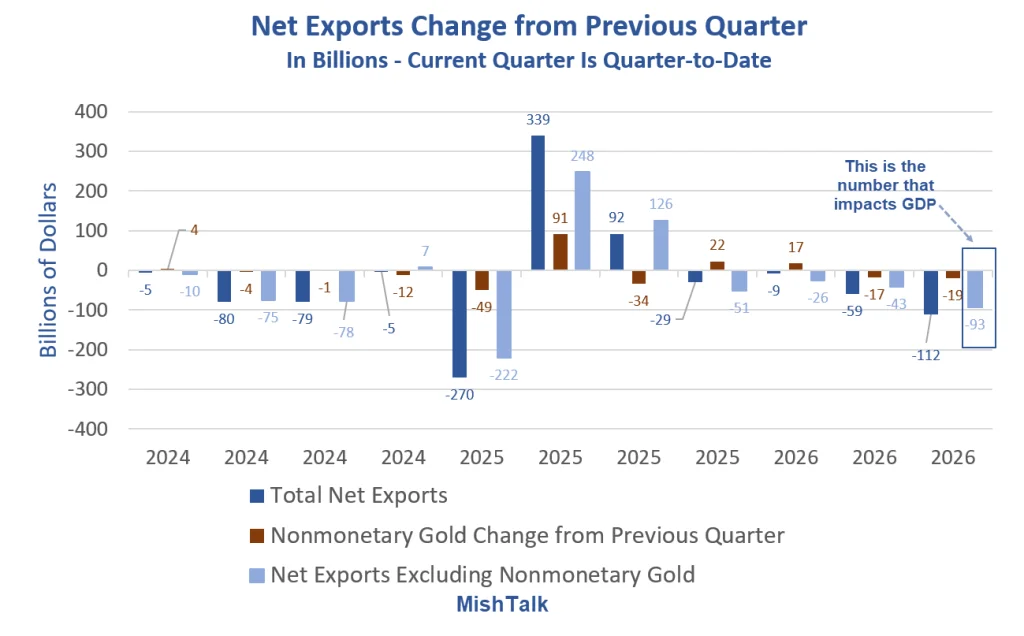
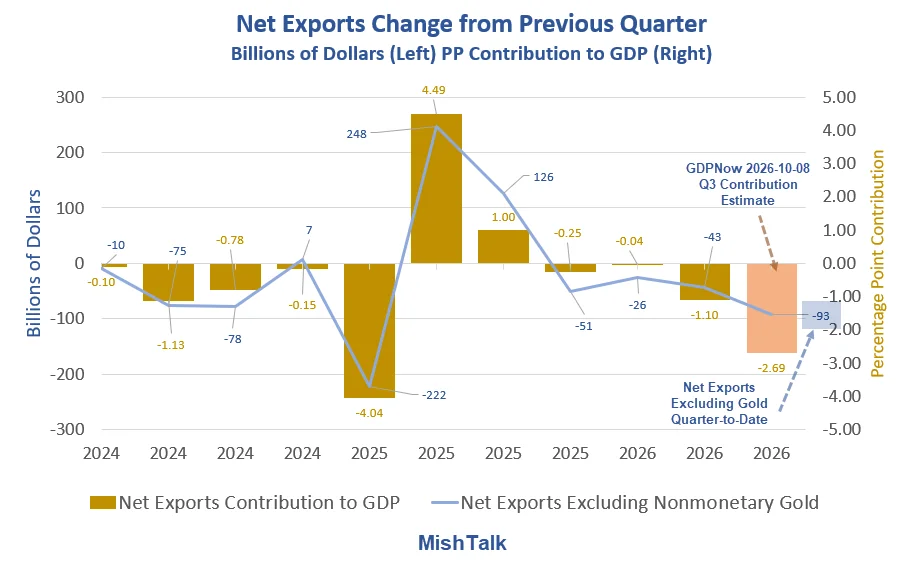
The stark contrast in net exports reflects an estimated decline of $93 billion in nonmonetary gold's impact on net trade balance for Q3 2026, positioning it as the largest negative trade figure recorded since Q1 2025, when the U.S. experienced a net trade loss of $222 billion. This isn’t merely a number on a report; it forms the backdrop for understanding the U.S. trade narrative. Without these fluctuations in gold trade, the overarching narrative around the overall trade deficit remains grim. Past periods have also showcased massive trade deficits, largely driven by fluctuating import demands and supply chain disruptions, but none so revealing as the current trend in gold exports. The connection between nonmonetary gold trading and larger trade deficits cannot be overstated; as volatility here rises, so too does the risk profile of the economy.
Historical Context of Trade Deficits
| Trade Era | Net Exports Excluding Nonmonetary Gold | Underlying Economic Catalyst | Macroeconomic GDP Impact |
|---|---|---|---|
| 2020 Q2 (Pandemic Nadir) |
-$181.0 Billion | Global lockdowns disrupting trade flows, freezing shipping lanes. | Contributed to a record -31.2% contraction in GDP. |
| 2022 Q1 (Stimulus Aftershock) |
-$104.0 Billion | Post-pandemic surges in consumer demand amidst supply shortages. | Contributed to a negative real GDP growth of -1.6%. |
| 2025 Q1 (Tariff Front-Running) |
-$222.0 Billion | Panic-driven stockpiling ahead of anticipated tariffs. | Prolonged effects on GDP models until recalibrated. |
| Current Q3 2026 (Estimate So Far) |
-$93.0 Billion | Strong demand for AI infrastructure and tech assets. | Subtracts -2.69 percentage points from GDP calculations. |
Despite the sharp decline that nonmonetary gold exports signify, recent GDPNow estimates still anticipate a growth rate of about 3.7% as of early October 2026. This disconnect between the anticipated growth and trade evaluations calls for scrutiny. How can GDP soar while trade deficit numbers falter? It suggests that growth may be fueled by sectors largely insulated from export activities. If you're working in this space, keeping an eye on these diverging paths is essential. Maintenance of a healthy economy relies not just on growth numbers but on trade balances that reflect sustainable practices.
Implications and Future Outlook
- Nonmonetary gold’s role in trade reports has diminished significantly, as evident from the reduced quarter-to-date net exports of only $2 billion.
- The broader trade balance is a trend to monitor closely. With imports surging along with corporate demands, we're likely entering a new phase in trade dialogues.
As analysts continue to evaluate the implications of nonmonetary gold activity on economic analyses, the relationship between trade deficits, GDP performance, and market sentiment remains cloudy. The complexity of these interactions means stakeholders should be prepared for further changes as underlying economic conditions evolve. And yet, one can't help but wonder—does the careful exclusion of nonmonetary gold from trade calculations serve an agenda? The relationship between gold's trade patterns and economic stability is intricate, inviting skepticism and critical attention from both economists and policy makers alike.