Term Spread as a Recession Indicator: Analyzing Post-2024 Predictions
The term spread model indicates recession probabilities, but recent data may misrepresent future outcomes, especially regarding 2024 predictions.
The term spread, particularly the difference between long-term and short-term interest rates, serves as a significant metric for assessing potential recession risks. Economists frequently utilize this model to forecast economic downturns, and recent analyses extend this methodology to assess predictions beyond 2024.
Understanding the Term Spread Model
The basic premise of the term spread model relies on comparing yields from long-term Treasury bonds, such as the 10-year, with shorter-term instruments like the 3-month Treasury bill. A common interpretation within this framework is that an inverted yield curve—where short-term rates exceed long-term rates—often precedes economic downturns. Historical data confirms this trend, highlighting that significant shifts in this spread can foreshadow recessionary periods.
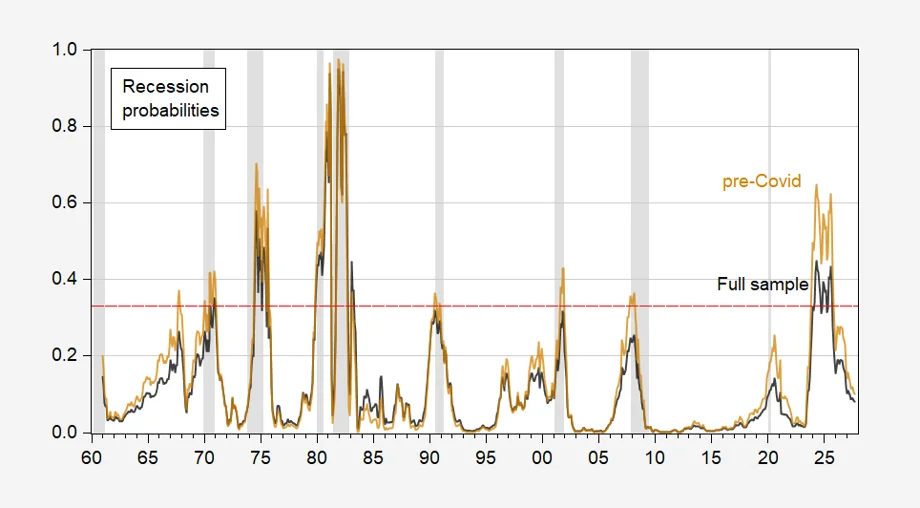
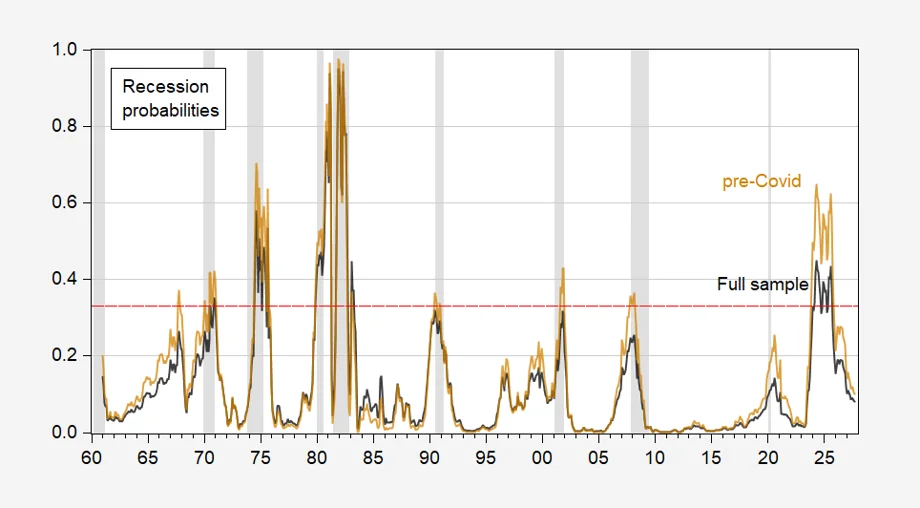
To visualize the model's effectiveness, researchers track estimated recession probabilities derived from a probit analysis of the 10-year to 3-month term spread against historical economic data spanning from 1960 to 2018. As demonstrated in relevant figures, a substantial portion of these estimated probabilities categorizes periods when economic contractions occurred, aligning with the dates defined by the National Bureau of Economic Research (NBER).
Reassessment of Recession Indicators
According to the analysis, using a 33% probability threshold derived from data prior to 2018 can help in defining recession indicators. This specific threshold appears adept at catching all post-1960 recessions, barring the anomalous pandemic-induced economic downturn. However, when applying a full-sample regression which factors in data until August 2026, the model produces misleading signals, notably a false positive prediction for the year 2024.
This discrepancy raises questions about the reliability of this approach. The regression's findings indicate that while the model captured all recessions in the identified timeframe, its broader application faltered by missing major downturns experienced during the 1990-91, 2001, and 2007-09 recession periods.
Quantitative Performance of the Model
The transition from a pre-2018 to a full sample analysis is telling. The pseudo-R-squared statistic, which reflects the model's explanatory power, diminishes from 0.30 in the pre-2018 analysis to 0.25 in the complete data set. This drop suggests a weakening correlation between the term spread and actual recession occurrences in the latter analysis, indicating that while the term spread remains a traditional tool for economists, its predictive capability may not be as robust as previously thought.
The implications of this recalculation are significant for stakeholders across the financial landscape, including investors and policymakers. An inability to accurately predict recession timings can lead to misallocation of resources, misinterpretation of market signals, and misguided strategic planning.
The Stakes for Stakeholders
For shareholders and finance professionals, the accuracy of recession predictions is pivotal. Incorrect forecasts can affect investment strategies, influencing stock valuations and market activities. Companies leaning on the term spread for guidance might find themselves unprepared for economic shifts, leading to consequences ranging from cutbacks to restructuring.
Furthermore, employees of organizations may also face uncertainties stemming from predictive failures. A downturn, when anticipated inaccurately, can disrupt employment continuity, affect morale, and challenge workforce stability. Employees may find themselves facing layoffs or budget cuts, driven by decisions stemming from misguided market expectations.
Looking Ahead: What's Next?
As we approach 2024, the financial community must approach term spread analysis cautiously. The potential for misleading indicators necessitates a more nuanced approach that combines various economic indicators alongside the term spread. Analysts should consider integrating additional variables such as consumer confidence, unemployment rates, and inflation measures, which collectively provide a fuller picture of economic health.
Policy adaptations will also likely play a role in shaping economic outcomes. Central banks and decision-makers should remain vigilant to the changing dynamics illustrated by current models to wisely navigate future challenges. The interplay of fiscal and monetary policies could influence the predictive capabilities of the term spread moving forward.
In conclusion, while the term spread has traditionally served as a respected gauge of recession potential, its current application and reliability warrant critical scrutiny. With the economic landscape continuously evolving, staying informed about the limitations and adaptations of this model will be crucial for all stakeholders involved in financial decision-making.