Rhodium Market Faces Surplus Amid Shifting Demand Dynamics
TD Commodity Strategy forecasts a rhodium surplus in 2024, signaling a shift following years of deficits, though supply vulnerabilities may trigger price spikes.
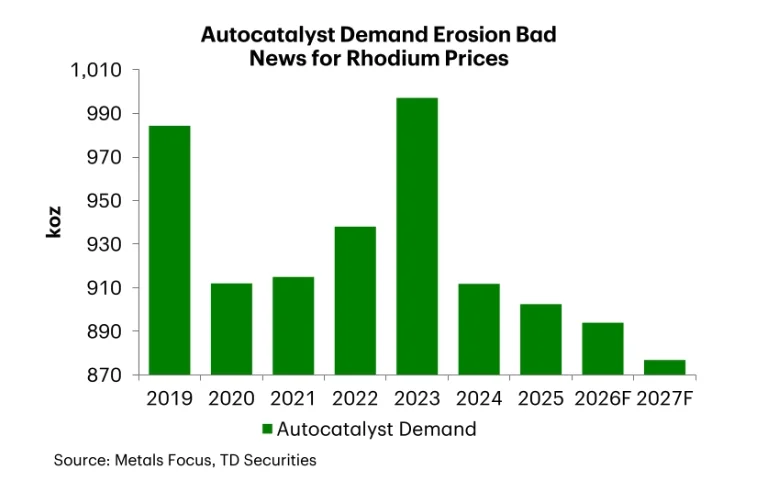
Rhodium prices are set to decrease as a result of dwindling demand from the autocatalyst sector, potentially leading to a market surplus in the coming year. TD Commodity Strategy indicates that after four years of deficits, a projected surplus of 20,000 ounces could emerge in 2024, driven by an increase in both mined and recycled supply against a backdrop of flat or declining consumption.
The current price of rhodium is approximately $9,000 per ounce, but TD anticipates a gradual decline to $7,600 in 2027 and further to $6,500 by 2028. This anticipated shift would mark the first surplus since 2022, following a significant deficit of around 50,000 ounces forecasted for this year. Notably, TD acknowledged that the surplus might have arrived sooner if not for production delays at South Africa's Amandelbult platinum-group metals mine due to shaft collapses occurring in 2025.
Supply Chain Vulnerabilities
One of the critical risks complicating the rhodium market is its fragile supply chain, particularly due to the long processing cycle typical of rhodium production. According to TD, the time required to transition material from mine production to refined rhodium exceeds three months. In contrast, platinum and palladium can be processed in just over a month.
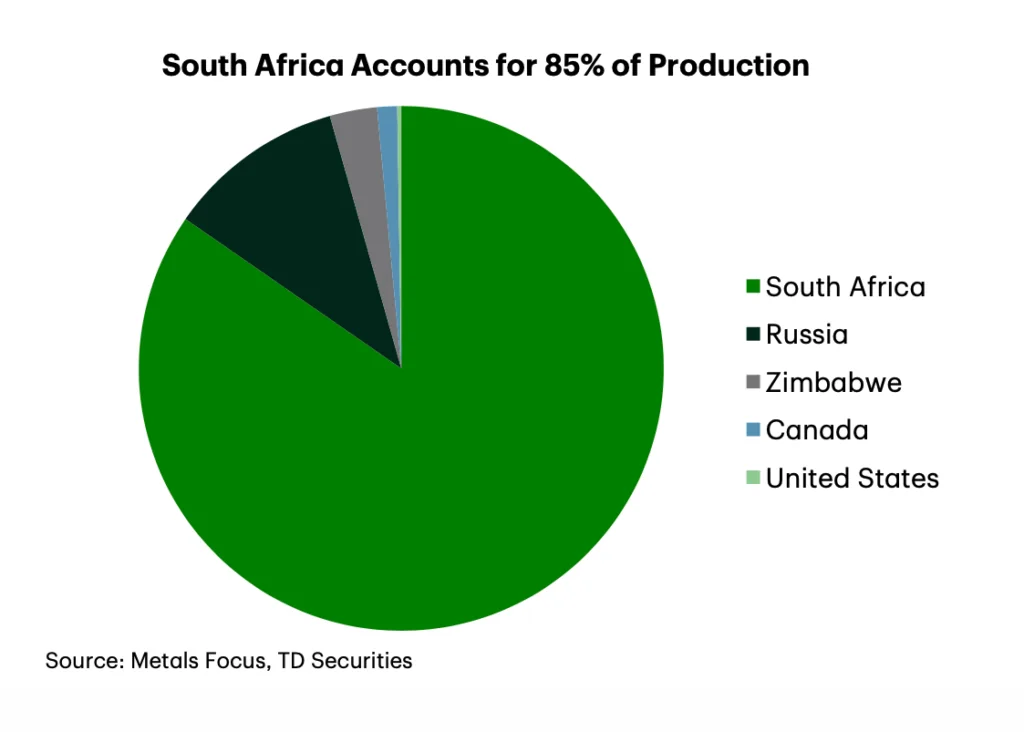
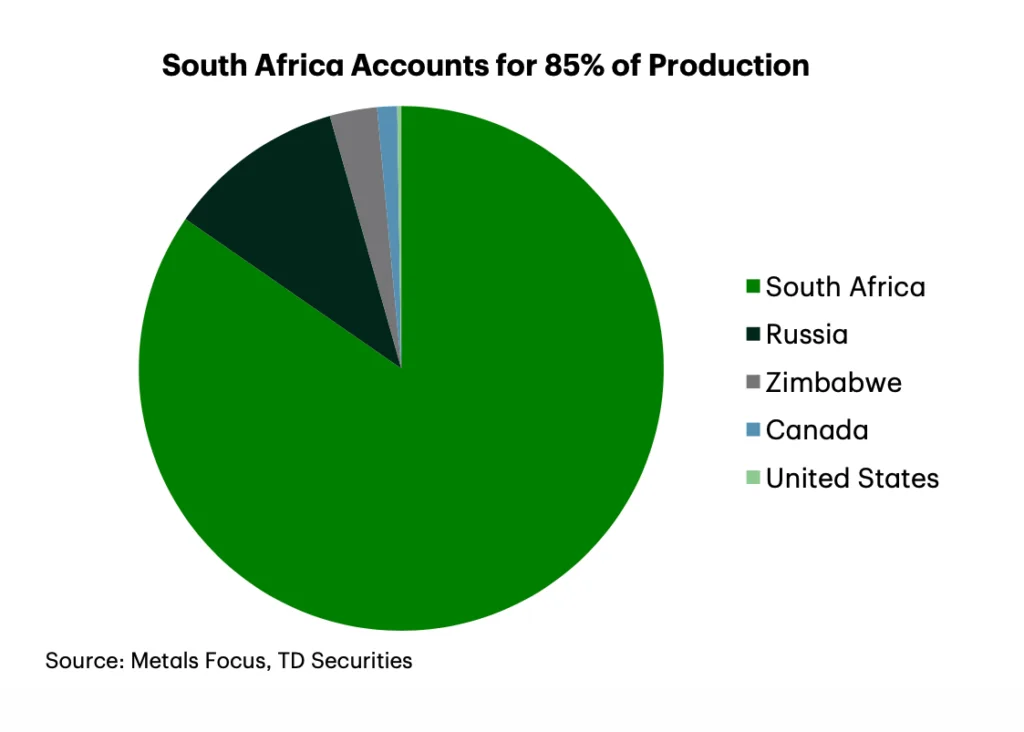
This extended timeframe means that the industry is especially susceptible to price spikes even as the market trends toward surplus. Production is currently operating near full capacity, meaning any disruption in supply could leave producers scrambling to meet demand. The situation is exacerbated by the geographic concentration of rhodium production; South Africa alone accounts for about 85% of the world's primary rhodium output, with only five mines responsible for roughly half of global production. Smaller operations in South Africa, along with mines in Russia and Zimbabwe, fill in the remaining supply.
Moreover, rhodium production is largely a byproduct of platinum and palladium mining. Its contribution constitutes only about 25% of the total revenue derived from mined platinum group metals (PGM). This interconnectedness implies that shifts in the broader PGM market could lead to sustained production levels even amid decreasing rhodium demand, thus complicating the market's response to supply disruptions.
Demand Dynamics Shift
The more persistent challenge facing rhodium remains its demand, primarily driven by its use in autocatalysts. As such, the metal's future is closely tied to the production of internal combustion engine (ICE) vehicles, which has stagnated as electric vehicles (EVs) increasingly penetrate the market. TD predicts a further decline in ICE vehicle sales, which would likely exert additional downward pressure on rhodium consumption.
In the near term, slower-than-expected adoption of EVs could soften the declines in rhodium demand and help stave off a prolonged price collapse. Additionally, the longevity of vehicles currently on the road continues to delay the re-entry of rhodium from older catalytic converters into the recycling market. Nevertheless, secondary supply is expected to grow steadily as aging vehicles with higher rhodium loadings reach the end of their lifecycles. The allure of high metal prices has further spurred recovery efforts from scrap, although recycling processes face limitations due to suboptimal recovery rates and inadequate processing capacity in various vehicle-retirement markets.
Substitution can act as a mitigating factor against falling rhodium demand. Palladium often acts as the alternative, though TD estimates that the transition can require 18 to 24 months and necessitates five to eight times the quantity of palladium to replace rhodium effectively.
Interestingly, investor interest in rhodium appears to be reviving. For the first time in over a decade, rhodium exchange-traded funds (ETFs) have recorded positive inflows, as both retail and institutional investors seek exposure to physical precious metals. However, holdings in these funds still significantly lag behind levels observed in the early 2010s.
The rhodium market is currently caught in a precarious balance between a waning long-term demand trend and a supply chain that lacks sufficient buffers for coping with sudden disruptions. This scenario suggests a future characterized by lower prices over the next several years, with conflicting pressures leading to potential price surges in response to sporadic production issues.