Top Mining Companies Face $264 Billion Setback as Gold and Lithium Markets Struggle
The top 50 mining firms saw a staggering $264 billion decline in September, primarily driven by falling gold prices and a sharp pullback in lithium stocks.
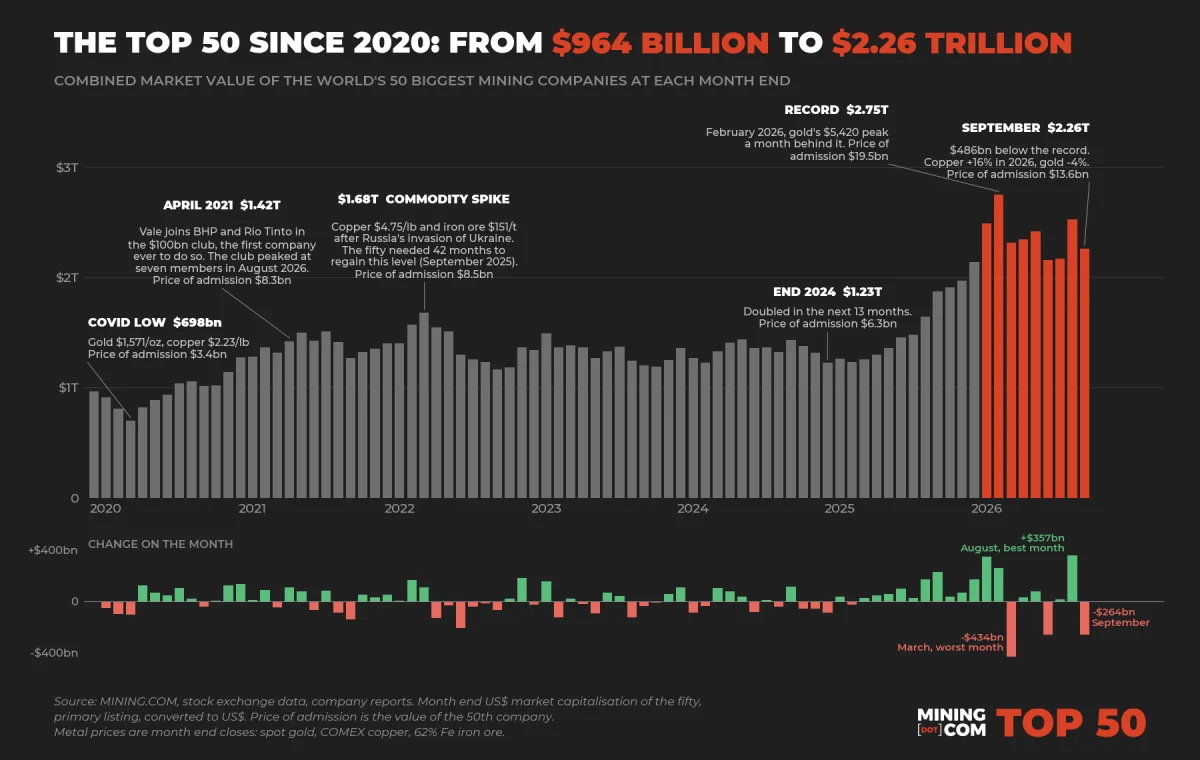
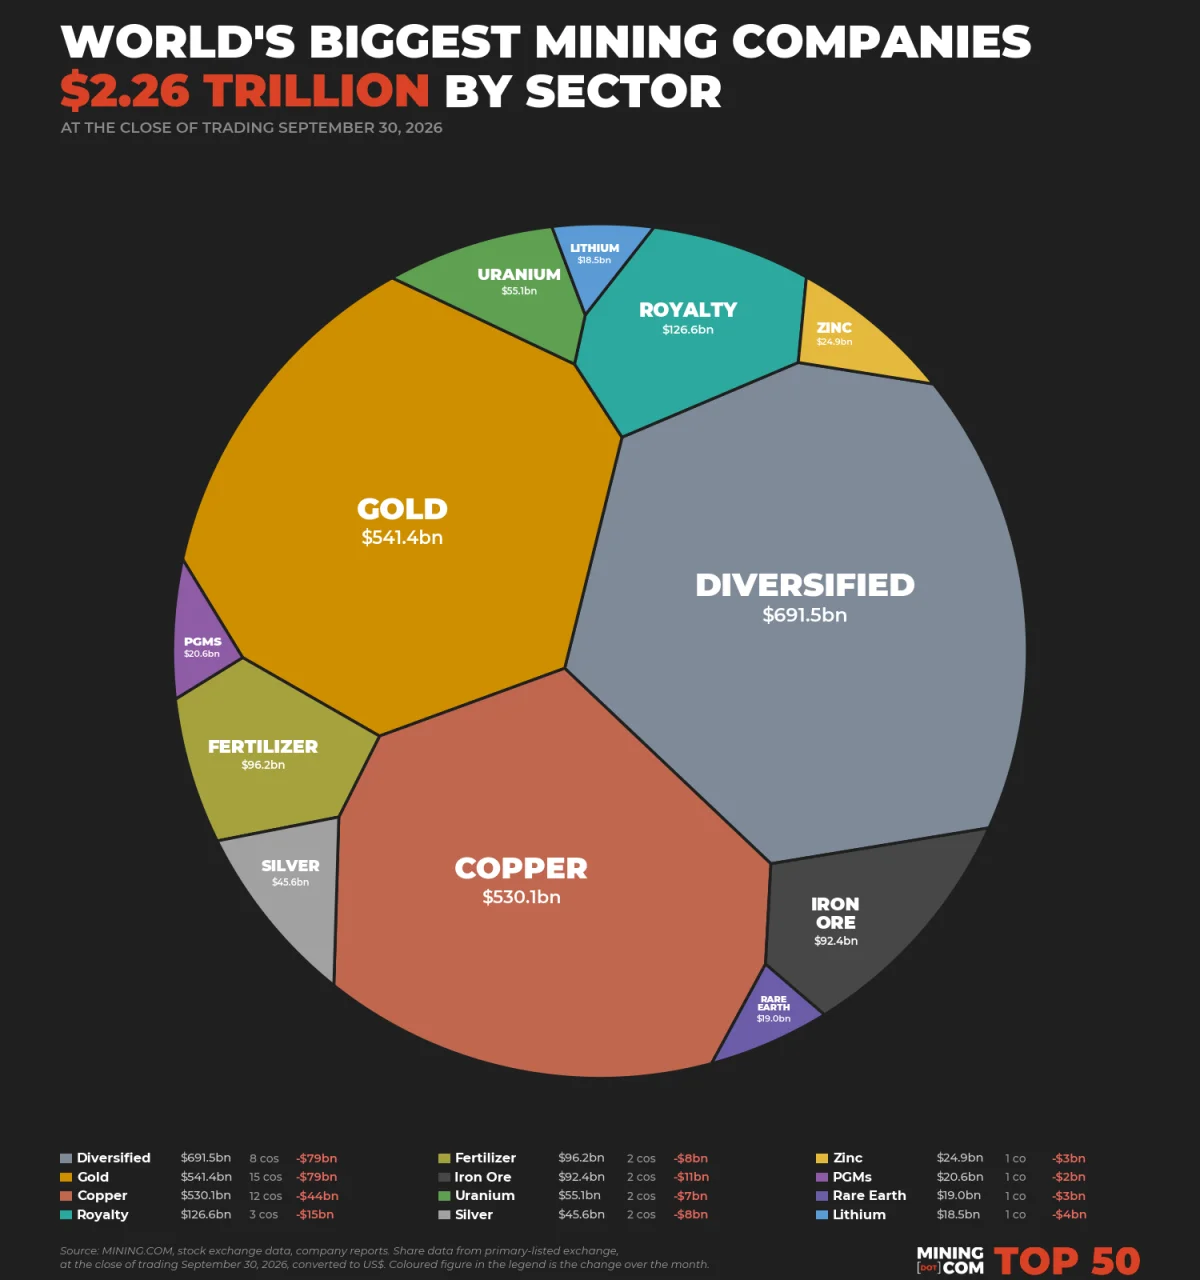
The collective valuation of the world’s 50 foremost mining companies plummeted to $2.26 trillion as of the end of September 2026, marking the second most severe monthly decline in the ranking's history. This downturn significantly reversed three-quarters of August’s remarkable $357 billion increase, primarily attributed to the volatility in the gold market.
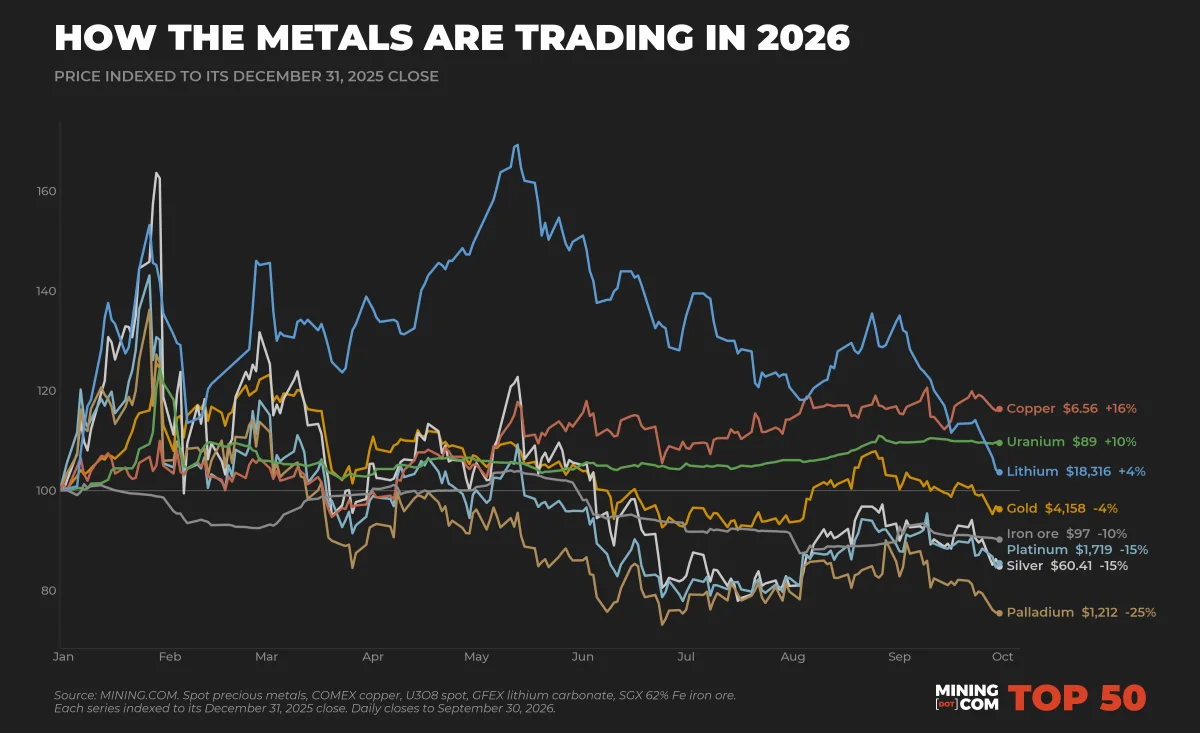
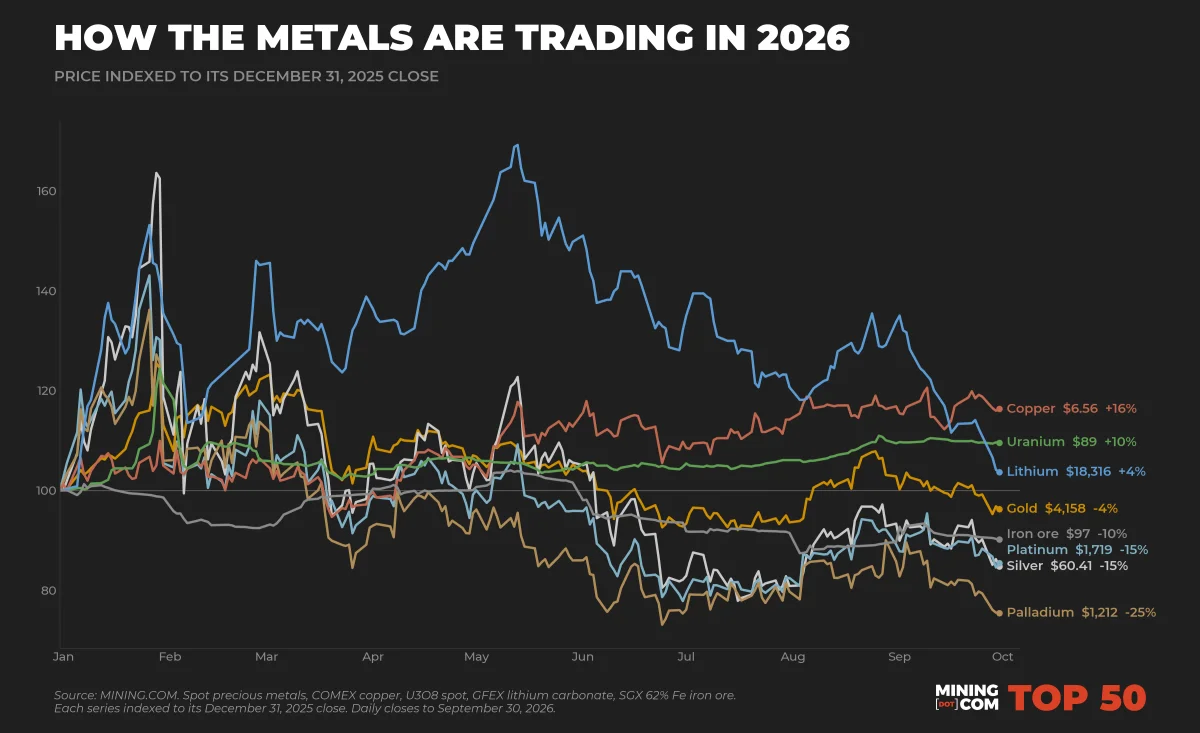
At the close of August, gold prices stood at $4,441 per ounce, but by the end of September, they had dipped to $4,158, reflecting a 6.4% decline. This drop has now pushed gold prices below the level at which they started the year, complicating the investment outlook as market dynamics shift. Key factors contributing to this downturn include the Federal Reserve's rate hike on September 16 — the first increase since the start of 2023 — coupled with a global bond market selloff that drove yields to heights unseen since 2008. The strengthening dollar didn't help gold's predicament either.
As gold faltered, silver faced an even harsher fate, falling 9% during the month. Meanwhile, PGMs (platinum group metals) continued their downward trajectory, while copper and iron ore showed some resilience, finishing the month nearly at the same prices as they began. Lithium, once the darling of the market, lost over 20% of its value in September alone, and now presents only a modest gain for 2026.
Gold Sector in Decline
The gold mining sector, which had contributed a remarkable $138 billion to August's total increase, witnessed a sharp fall, losing $79 billion in September — a decrease of 12.7%. Notably, no gold miner within the top rankings reported an increase in value for the month. Companies like Newmont and Agnico Eagle suffered substantial losses, each decreasing by double-digit billion dollar amounts, pushing Agnico back under the critical $100 billion valuation after briefly surpassing it.
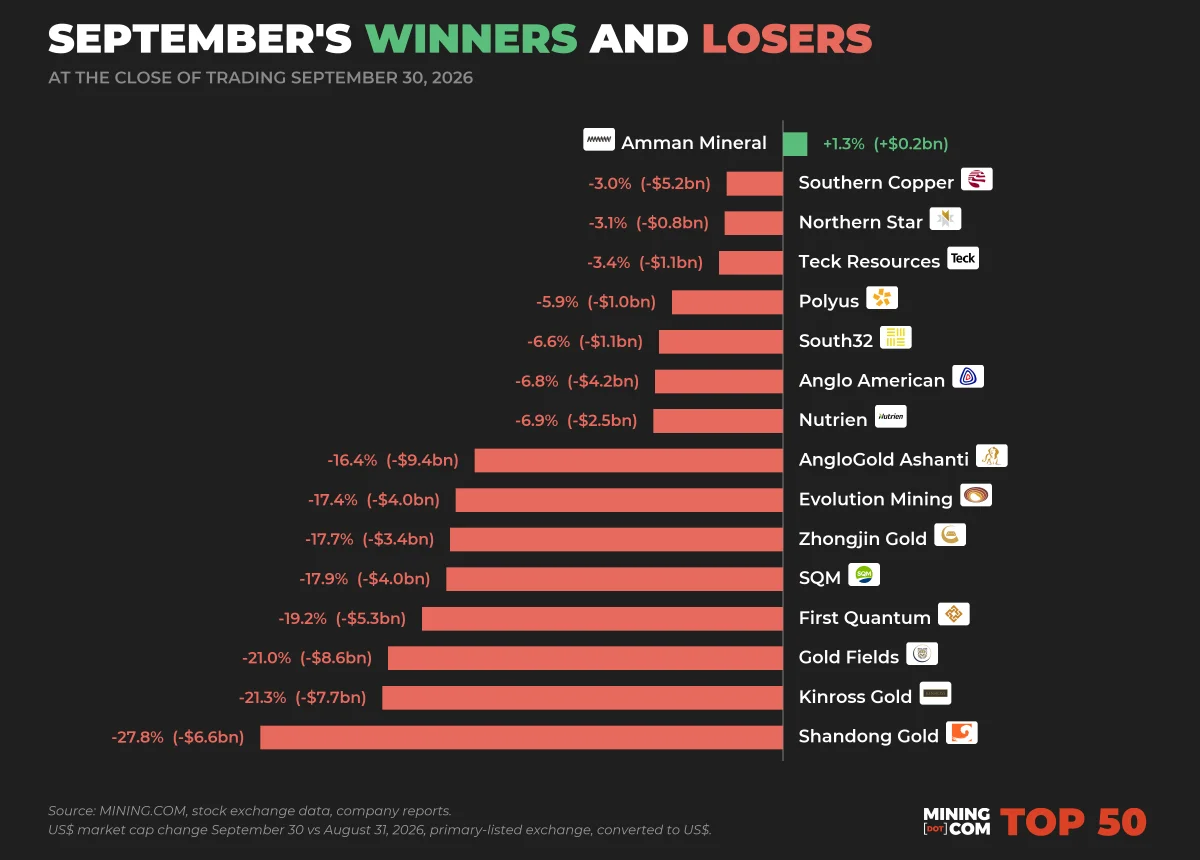
Among the biggest losers, Kinross Gold plummeted 21.3% after reducing its production guidance for 2026 and 2027 by around 8%, citing issues such as adverse weather conditions and declining ore grades in its mining operations. This led to a significant drop in share price, with a notable decline in a single session.
Shandong Gold faced even steeper declines, falling 27.8% after revising its 2026 mined gold target down to between 1.16 million to 1.22 million ounces, compared to a previous goal of at least 1.58 million ounces. Zhongjin Gold also reported a 17.7% loss.
Ambitions Backfire for Gold Fields
Gold Fields made headlines with its A$38.7 billion ($27 billion) bid for Northern Star, a proposal intended to create the second-largest gold producer globally. However, Northern Star's board dismissed the offer, deeming it "highly opportunistic." This rejection resulted in a 12% drop in Gold Fields' stock on the response day, concluding the month down 21% and erasing approximately $8.6 billion in market capitalization. As a result, Gold Fields is now reportedly considering augmenting its offer with a larger cash component to revive negotiations.
Interestingly, despite the surrounding turmoil, Northern Star managed to maintain its relative position, being the best performer among its peers at only 3.1% down.
Copper Market Stagnation
Turning to copper, producers within this category collectively incurred a $44 billion loss, translating to a 7.6% decrease. Copper prices ended the month at $6.56 per pound ($14,500 per tonne), slightly below their starting point. During September, copper saw record highs but subsequently lost momentum due to hesitations regarding a proposed US tariff.
Southern Copper, a key player, saw its market value drop by 3% to $171 billion. This company briefly displaced Rio Tinto from the second spot in the rankings earlier in the year but reverted back after losses in September, ending the month $9.9 billion shy of Rio Tinto, which fell 8.9% amid stagnant iron ore prices.
Notably, BHP faced the largest dollar loss of any firm in the rankings, with a staggering $26.4 billion decline or 11%. This was largely attributed to operational disruptions following a fatal incident at its Escondida mine, leading to temporary suspension of operations amidst discussions of a worker strike. Freeport-McMoRan narrowly retained its position above the $100 billion threshold, with a 7.6% dip.
The only copper company to post gains in September was Amman Mineral, an Indonesian firm, which increased by 1.3% thanks in part to plans to double copper cathode output.
Tricky Times for Lithium
The lithium sector emerged as the biggest underperformer in September, with carbonate futures plummeting 22.5% to 122,800 yuan ($18,300) per tonne, the lowest level recorded since the beginning of the year. This decline reflected a staggering 39% drop from the two-year highs reached mid-May.
While supply disruptions were anticipated, the catalyst for the downturn originated from a change in inventory reporting methodology at a Chinese agency, which unexpectedly elevated the reported stockpiles by more than double to 175,000 tonnes, causing prices to drop sharply.
After surging nearly 70% earlier in 2026, lithium is now showing just a scant gain of less than 4%. Several equities have been significantly affected, with Albemarle and Ganfeng Lithium each losing over 20% of their value in September, now trading at less than half their peak prices.
At the end of August, three lithium producers were in the rankings; however, with the September downturn, only SQM remains at the end of September, down from six slots during the peak EV demand in late 2022. The threshold to be included in the top 50 dropped to $13.6 billion from $15.6 billion in August, marking the lowest cutoff since June.

Zijin Mining’s Struggles
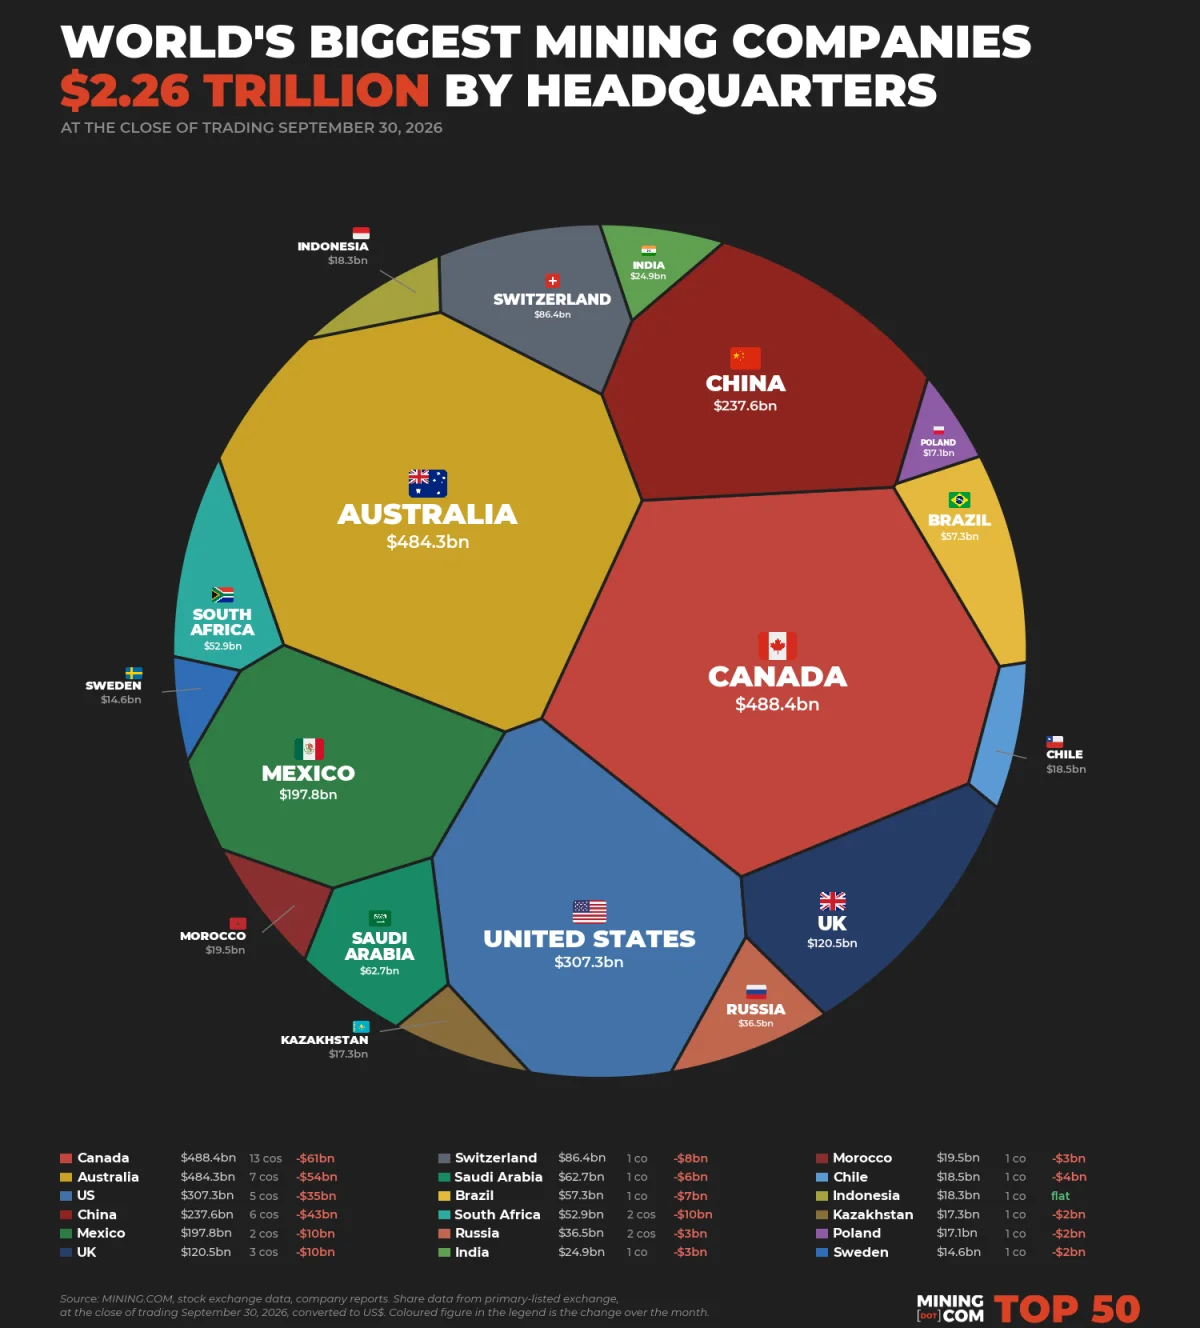
In the broader context, every mining region suffered losses, with Chinese firms notably losing $43 billion collectively, which represents a 15% drop in their combined market value. Zijin Mining accounted for $19 billion of this decline, falling by 14.2% to $115 billion. The company faced similar pressures to its peers, especially as gold prices dropped.
Canada's mining sector reclaimed its lead over Australia as the most valuable mining hub, valued at $488 billion versus Australia’s $484 billion. This shift was catalyzed by the decline of BHP’s market value outpacing any positive movement from Canadian companies. The United States remains third, with a total valuation of $307 billion.
A Historical Perspective
September's $264 billion loss ranks as the second-largest monthly decline since late 2019, behind March's staggering $434 billion drop during a prior gold slump. Regardless, the third quarter ended with a net increase of $107 billion compared to its opening valuation, signaling resilience in the broader market as the ranking remains $118 billion above the close of the previous year.
Over a longer timeline, the companies' values have seen significant fluctuations. After hitting a low of $698 billion at the Covid-related market low in March 2020, mining firms took nearly three and a half years to return to the $1.68 trillion mark seen during the 2022 commodity spike. The ranking has since doubled in value to its current standing of $2.26 trillion, which is about $486 billion, or 18%, lower than its peak in February.
The stark reality for many mining companies is the significant gap to their individual 52-week highs. If every firm had closed at its 52-week high, the ranking would have exceeded $2.97 trillion, reflecting a $709 billion excess compared to current valuations. Many of these peaks were set just recently, with a large number of companies hitting their highs as gold prices surged earlier in the year.
In summary, the mining sector's current valuation landscape underscores the volatility driven by shifts in commodity prices and market sentiment. The challenges faced by gold and lithium specifically reveal broader trends and potential risks that may influence market dynamics in the near future.