Potential Disruptions in Red Sea Traffic Threaten Mining Supply Chains
The Bab el-Mandeb Strait disruption could significantly impact mining supplies, causing cost increases and delays for essential materials, according to GEM Mining Consulting.
A sustained disruption around the Bab el-Mandeb Strait, a crucial maritime passage for Red Sea traffic, poses serious risks to mining supply chains, extending far beyond impacts on oil and gas. This situation threatens to escalate costs and delay vital materials necessary for mining operations, including sulfuric acid, explosives, and battery components, according to an analysis from GEM Mining Consulting.
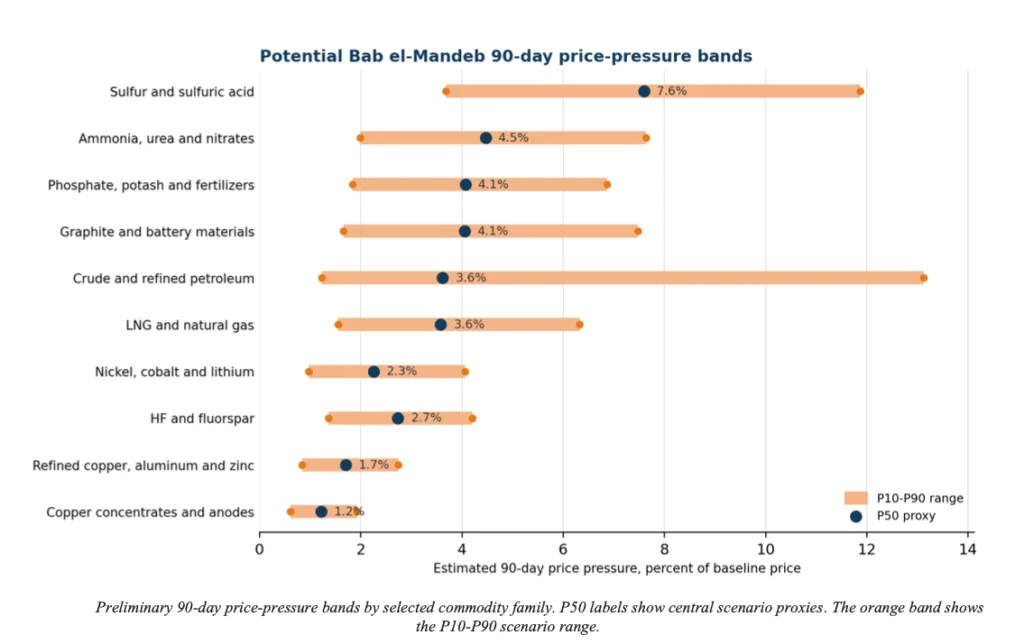
GEM estimates that a potential disruption lasting 90 days could affect commodity flows ranging from 38.9 million to 77.8 million tonnes, with a median scenario predicting an impact of 61.1 million tonnes. Such disruptions could delay mine production between 0.8 million and 13.8 million tonnes, while demand could also see delays ranging from 12.6 million to 33.7 million tonnes.
In terms of financial implications, GEM’s modelling indicates price increases could range from 1.2% to 10.5%, with a central estimate of 3.4%. The resulting cost premiums are projected to span from $480 million to $2.48 billion, with the most likely case landing at $1.37 billion.
Geopolitical Tensions in the Red Sea
Recent developments in Yemen have intensified geopolitical concerns surrounding Bab el-Mandeb. Houthi militants, backed by Iran, have gained control of the Greater and Lesser Hanish Islands, further solidifying their influence around this pivotal shipping corridor. This escalates fears about their potential to disrupt not just oil shipments, but also the vital materials that feed into mining and other industrial sectors.
Bab al-Mandeb forms the southern gateway to the Red Sea, and its narrow passage is essential for the flow of goods from the Gulf of Aden and the Indian Ocean to the Suez Canal and ultimately to Europe. It accounts for about 10% of global maritime trade, underscoring the gravity of any long-term disruptions. These concerns are magnified as Saudi Arabia has recently shifted some oil shipments through the Red Sea, especially in light of disruptions in the Strait of Hormuz.
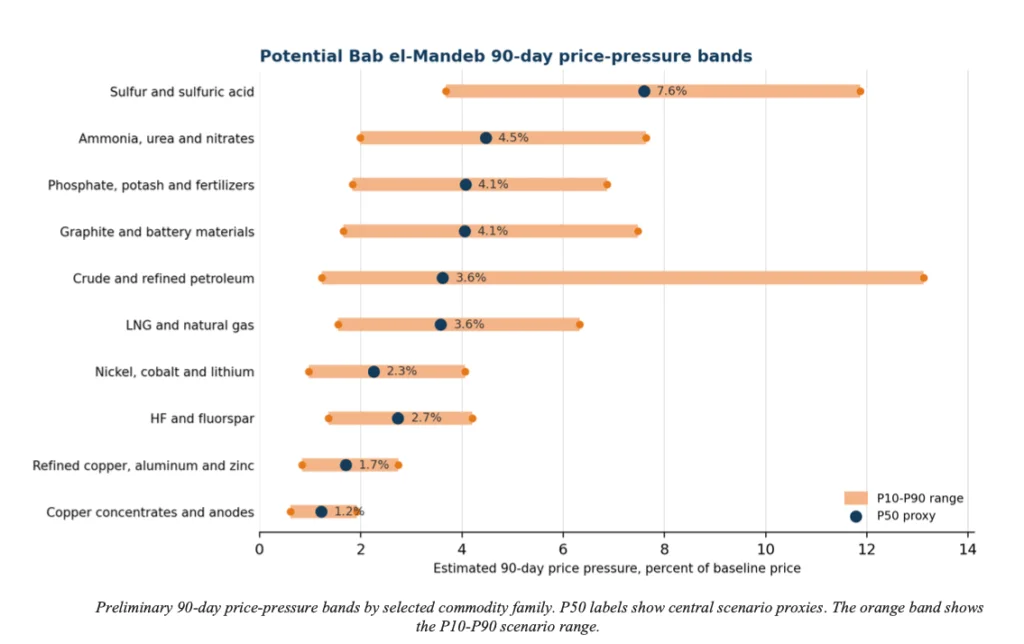
While the immediate focus has been on oil supply, GEM’s findings suggest that the mining sector could experience ripple effects through increased freight rates, insurance costs, and delayed acquisition of necessary chemicals and materials for mine operations.
Critical Inputs at Risk
According to GEM, several vital inputs identified as particularly vulnerable include sulfuric acid, ammonia, nitrates, phosphate, and potash fertilizers, along with graphite and battery material intermediates. The elevated risk stems from their reliance on specific shipping routes, limited ability to substitute materials quickly, and their importance in various industrial processes.
Notably, sulfuric acid is indispensable in many mining operations, while ammonia and nitrates are integral to the explosives supply chain. Specialty chemicals and essential components for battery manufacturing often depend on specific suppliers and tightly controlled logistics networks.
GEM’s analysis incorporates a heat map rating these commodity families across six metrics: route share, ease of supplier switching, inventory risk, market dynamics, freight risk, and ties to industrial processes. Categories such as petroleum products, LNG, sulfuric acid, and battery materials rank high on this vulnerability scale due to their reliance on shipping routes and limited inventories. In contrast, bulk commodities like iron ore and metallurgical coal seem less susceptible to immediate disruptions due to their market size and the availability of alternative routes.
The figures provided by GEM should be seen as scenario bands rather than definitive forecasts. They are framed within a range of expected impacts and do not operate as statistical quantiles, meaning they require careful calibration with relevant data on trade flows and inventory dynamics.
Strategies for Resilience
The findings highlight a need for mining companies to reevaluate their maritime risk exposure, positioning shipping chokepoints as critical operational concerns rather than mere geopolitical issues. Companies should consider strategies such as mapping supply routes, performing stress tests on inventory levels, and identifying which facilities might be the first to face constraints if disruptions last for various durations like 30, 90, or even 180 days.
Backup suppliers and alternative logistics solutions will be vital, especially for inputs without easily attainable substitutes. By proactively addressing these vulnerabilities, firms can mitigate potential risks associated with maritime disruptions.
Moreover, governments can reinforce mineral security by integrating strategic maritime routes into their planning protocols, enhancing transparency around trade flows, and coordinating international efforts on maritime security to safeguard these crucial supply channels.
As the geopolitical landscape continues to evolve, the potential for disruptions in the Red Sea remains a key factor that could influence mining operations and supply chains worldwide. Investors, operators, and regulators must remain vigilant in assessing and responding to these emerging risks.