Understanding Retail Investors' Growing Role in the Gilt Market
Retail investors are increasingly participating in the UK gilt market, influencing liquidity dynamics and presenting new implications for monetary policy and financial stability.
Sarah Munson and Callum Ashworth
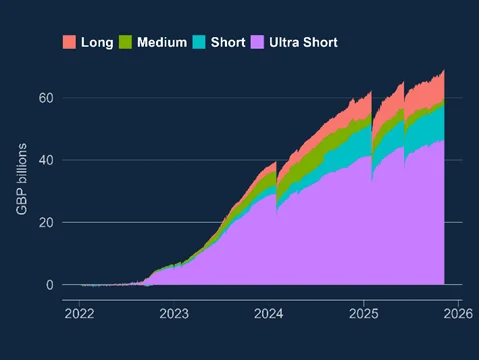

In recent years, retail investors have made substantial inroads into the UK government bonds market, commonly known as gilts. This shift reflects a broader global trend where individual investors increasingly manage their portfolios independently. Understanding the motivations behind this trend and its implications for both the gilt market and broader financial landscape is essential for investors and market analysts alike.
Characteristics of Retail Participation in the Gilt Market
Various characteristics of gilts appeal to retail investors, among which maturity and coupon rates are particularly significant. The residual maturity of gilts is classified into various categories: ultra-short (under 3 years), short (3-7 years), medium (7-20 years), and long (over 20 years). Additionally, the fixed annual interest rates, referred to as coupon rates, greatly influence investors' choices, as these rates determine the returns relative to the face value of the bonds.
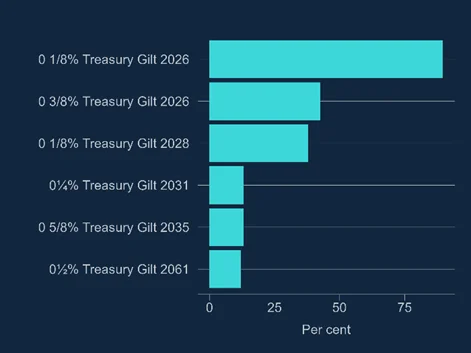
Utilizing data from the Markets in Financial Instruments Directive II (MiFID II), an analysis reveals that retail holdings are heavily concentrated in a narrow range of gilts, specifically those with shorter maturities and lower coupons. As shown in Chart 1, holdings are skewed towards ultra-short-dated bonds, with over 80% of retail positions in bonds within the bottom quartile of available coupon rates. Overall retail holdings, while still modest—accounting for less than 4% of total outstanding gilts—are becoming more concentrated in specific bonds, significantly affecting the free float available for trading.
Factors Driving Increased Retail Demand
The rising interest in gilts from retail investors can be attributed to several interlinked factors. A notable driver has been the shifts in gilt yields relative to cash savings accounts. As gilt yields rose, particularly in 2022 following increases set by the Monetary Policy Committee, retail demand surged. Conversely, there has been a softening of growth in 2025 as yields on shorter-term gilts slightly declined, albeit remaining elevated in comparison to levels prior to 2022.
Enhanced access to digital investment platforms and a wealth of educational resources have further propelled retail demand. User-friendly features such as real-time pricing and integration into Individual Savings Accounts (ISAs) and self-invested personal pensions (SIPPs) have lowered barriers for participation. Recent initiatives have also facilitated retail investors' access to primary gilt issuance through digital channels, embedding them deeper into the gilt market.
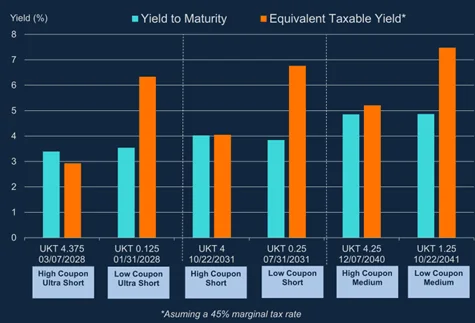
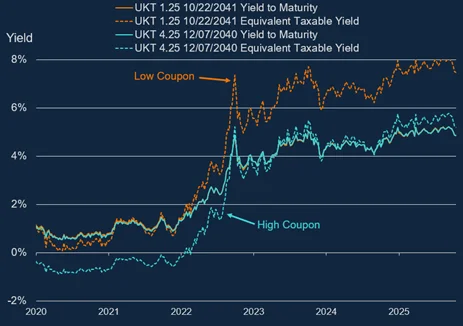
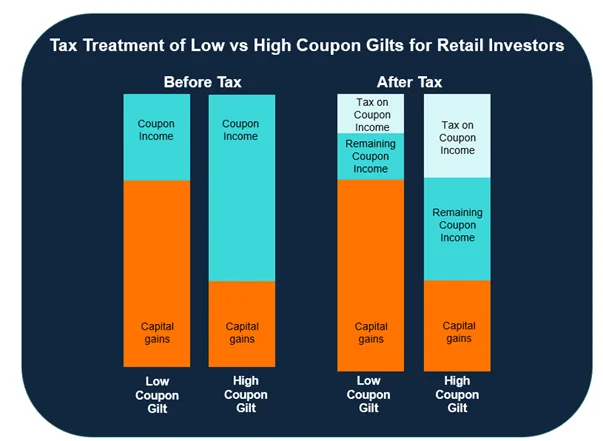
Additionally, tax advantages serve as a compelling incentive for retail investors in the UK. The exemption from capital gains tax on gilts enhances their attractiveness, especially for those focused on low-coupon bonds—where the bulk of returns stem from capital appreciation as these bonds near maturity. Although coupon payments are liable for income tax, the overall tax-adjusted yield for lower-coupon gilts can be more favorable than for their higher-coupon counterparts, especially during high yield environments. These dynamics are illustrated in Chart 3 and Chart 4, which show the interaction between gilt coupon rates and investor tax situations.
Implications for Market Dynamics
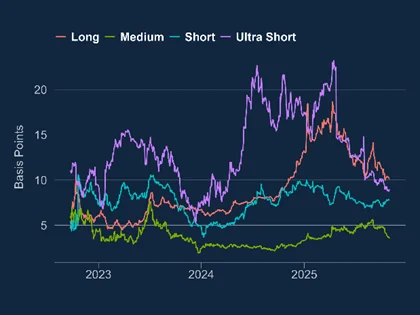
The growing presence of retail investors has implications for the dynamics of the gilt market and its liquidity. While aggregate data indicate that retail holdings have a limited impact on overall liquidity metrics, there can be significant liquidity effects in specific bonds that retail investors favor. The Bank of England, which keeps close tabs on the gilt market for its relevance in monetary policy transmission and financial stability, recognizes these trends as essential for maintaining market integrity.
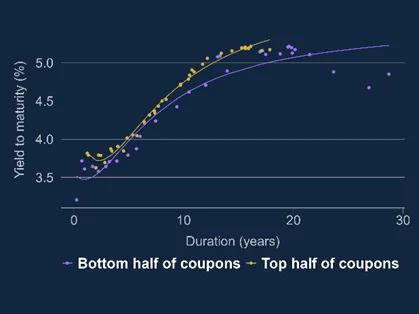
Research has demonstrated that different investor groups can influence gilt pricing, particularly in relation to maturity. As evidenced in past studies, retail investor activity has been associated with variations in performance among high versus low-coupon gilts. This divergence can lead to notable "yield curve noise," affecting perceptions of market health and liquidity conditions. For instance, in 2024, marked differences in yield performances between various coupon types indicated a lack of stability in perceived liquidity, complicating the analysis of market conditions.
Despite such challenges, the combination of growing retail interest in low-coupon gilts has driven "yield curve noise" to some extent, although this reflects a broader interaction of factors, including the appeal of these bonds to institutional investors. Additionally, the characteristics of low-coupon gilts, often classified as ‘off-the-run’ due to reduced issuance frequency by the Debt Management Office (DMO), shape market dynamics and investor behavior.
Outlook and Future Trends
As we move forward, the increasing participation of retail investors in the gilt market potentially broadens the investor base, which may aid in the effective transmission of monetary policy while enhancing financial stability. Although retail holdings presently remain modest in total scope, the concentrated nature of these investments in certain bonds could add pressures on liquidity in those specific areas.
The future of retail engagement in this market depends significantly on existing yield levels and the structural factors driving demand. It remains to be seen whether the current trends represent a fundamental shift in investor behavior or if they are temporary responses to prevailing market conditions.
In conclusion, as retail investors continue to carve out their niche in the gilt market, the interplay between their motivations and market dynamics will require close monitoring, particularly as the economic landscape evolves through the current easing cycle.
Sarah Munson works in the Bank’s Sterling Markets Division and Callum Ashworth works in the Bank’s Market Intelligence and Analysis Division.
If you wish to engage further, feel free to contact us at [email protected].
Comments will only be published after moderator approval. Participation requires full identification.