Understanding Collateral Re-use: Impacts and Risks in the Gilt Repo Market
This analysis highlights the mechanics of collateral re-use in the gilt repo market, revealing its benefits and significant risks during market turbulence.
Introduction
The practice of re-using securities as collateral is integral to the functioning of the repurchase agreement (repo) market. It enhances the availability of securities, contributes to lower funding costs, and helps facilitate liquidity under normal market conditions. However, collateral re-use also poses risks, particularly during times of market stress. It can intensify delivery failures and amplify volatility in repo rates. This article investigates the prevalence of collateral re-use in the gilt repo market and examines its procyclicality and implications for market stability.
Defining Collateral Re-use
Collateral re-use involves financial institutions utilizing securities received as collateral multiple times—typically in securities financing transactions such as repos and securities lending. This approach is particularly common in the repo market, where repo dealers play a vital role in ensuring smooth transactions of cash and securities across the financial landscape. Major players in this process include large dealer banks engaged in market-making activities and hedge funds that seek specific securities for trading strategies.
The scarcity of particular assets, notably government bonds, often drives the need for collateral re-use. When specific securities are limited—often due to significant central bank purchases—financial institutions adapt to these constraints by enhancing the re-use of their collateral to maintain market liquidity.
Mechanics of Collateral Re-use
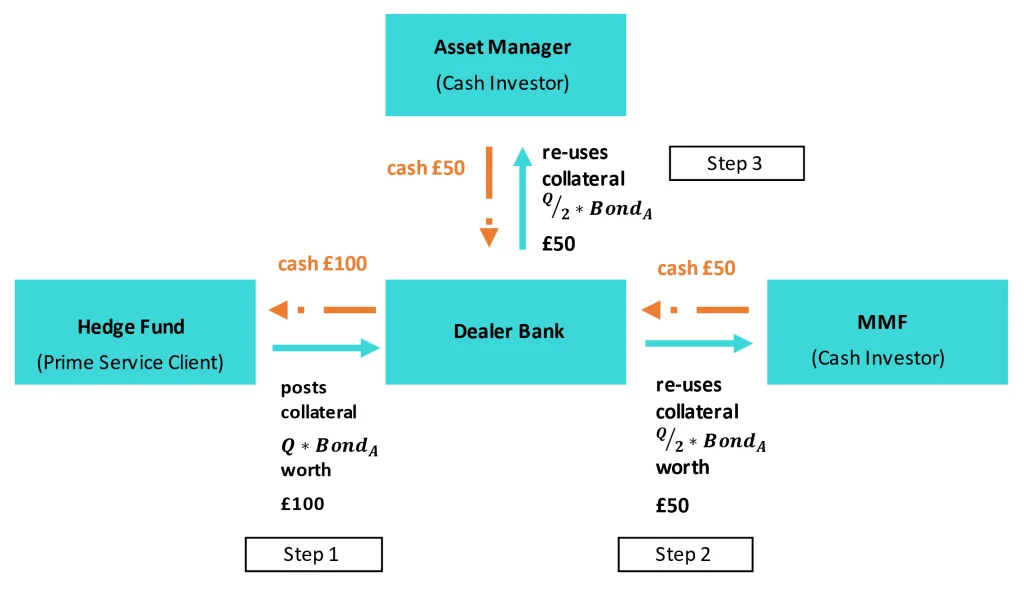
The mechanics of collateral re-use typically involve a chain of transactions among prime brokers, hedge funds, and money market funds. For instance, a hedge fund can post collateral—let’s say Bond A worth £100—to a dealer bank through a repo agreement, gaining access to the cash value of the bond. The dealer bank then re-uses this collateral, potentially splitting it between two cash investors: a money market fund and an asset manager, each receiving a proportionate share. This layered structure helps increase leverage for hedge funds while enabling dealer banks to finance their lending.
The Value of Collateral Re-use
Collateral re-use plays a crucial role in maintaining liquidity in financial markets. By enabling the re-circulation of received collateral, it broadens the pool of available high-quality assets and reduces capital costs for market participants. Such liquidity is essential for fostering investment and economic growth.
Despite these benefits, collateral re-use has previously been linked to financial crises, which raise concerns about the accumulation of delivery failures and heightened volatility within bond and repo markets. Uncertainty surrounding the extent of collateral re-use, especially during bankruptcy proceedings, poses systemic liquidity risks. This interconnectedness may lead to liquidity spirals and heighten the potential for widespread market disruptions.
Collateral Re-use in the Gilt Repo Market
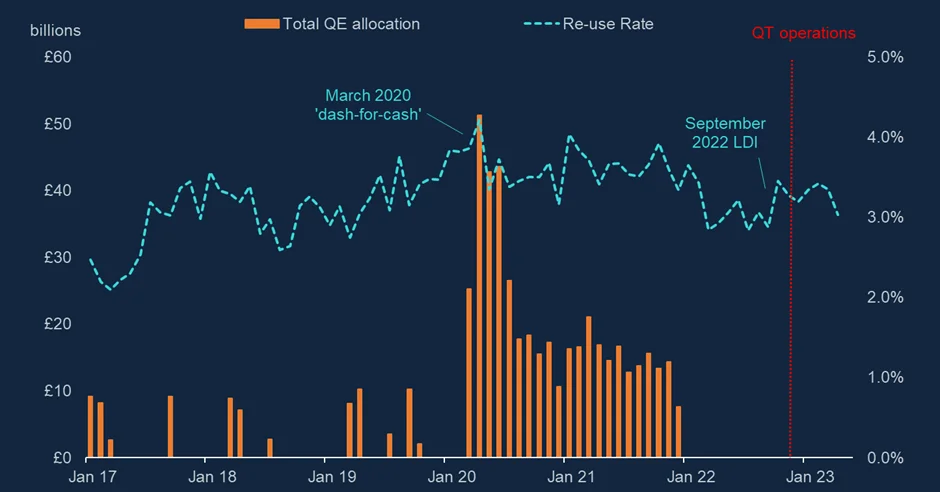
Data from January 2017 through April 2023 reveals that collateral re-use in the gilt repo market averaged around 3.5%. This figure indicates that a notable portion of gilt repos was secured using re-used collateral. There was a marked increase in collateral re-use between March 2020 and late 2021, coinciding with the Bank of England’s Monetary Policy Committee increasing its asset purchases by £450 billion, largely comprising UK government bonds. Such asset scarcity has subsided following adjustments by the MPC at the end of 2022, when it opted to reduce its holdings of government bonds.
Assessing Risks Associated with Collateral Re-use
Excess collateral re-use can emerge as a significant risk factor, especially during market stress. When multiple transactions are collateralized with the same assets, it breeds interconnectedness among market participants, increasing vulnerability to contagion and settlement failures. Given that over 85% of total repo stock in the UK consists of gilt-specific securities, the presence of these asset chains can amplify delivery failure risks significantly during periods of instability.
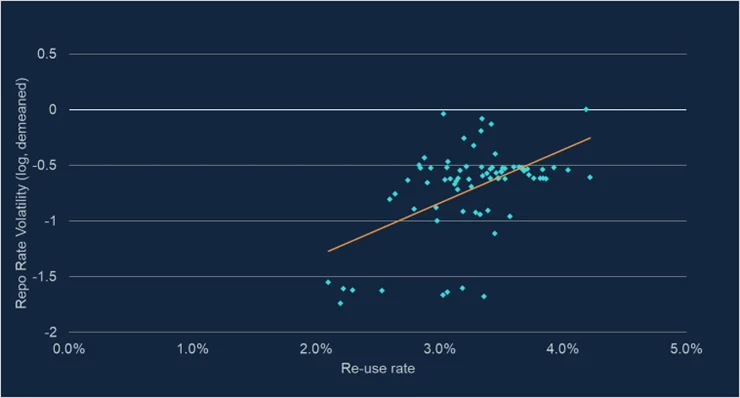
As traders respond to unexpected market shocks by demanding more liquidity—often hoarding high-quality securities—the situation can worsen under conditions of heightened collateral re-use. This hoarding constrains the availability of specific securities further, resulting in delivery failures. Research indicates a positive correlation (approximately 53%) between repo rate volatility and collateral re-use during the observed period, underscoring the necessity for closer monitoring and research into collateral dynamics.
Conclusion: The Need for Vigilance
The findings concerning collateral re-use in the gilt repo market reveal both advantages and significant risks inherent to this practice. While it supports liquidity and reduces capital costs under typical market conditions, it also heightens vulnerabilities, particularly in disrupted market environments. Ongoing research and vigilant monitoring of collateral re-use practices on a global scale are essential to enhancing macroprudential oversight and mitigating the systemic risks that could arise from interconnectedness within the securities financing markets.