Market Reactions to Negative Big-Tech Earnings: Understanding the Impacts and Implications
Negative earnings reports from major US tech firms lead to broader market declines, complicating typical flight-to-safety dynamics and prompting global implications.
Daniel Ostry, Roger Vicquéry, and Emilio Zaratiegui
Concerns are escalating among policymakers, international organizations, and big tech CEOs regarding the current artificial intelligence (AI) boom. Notably, the boom is increasingly viewed as detached from underlying economic fundamentals. The Bank of England’s February 2026 Monetary Policy Report highlights the risk of an asset price correction, and the July 2026 Financial Stability Report outlines a potential scenario for an AI correction. Our research examines how negative earnings announcements from big tech companies transmit information effects across global markets, revealing substantive impacts beyond the tech sector: equity indices tend to decline, credit spreads widen, and the US dollar depreciates. This pattern, alongside the limited response of Treasury yields, signals weak flight-to-safety behavior unlike that in past financial crises.

Unique Dynamics of an AI Market Correction
Why might an AI sector downturn affect markets differently than traditional financial shocks? The current confidence in the tech sector stems from its association with anticipated productivity growth across the economy. This belief has driven significant private sector capital inflows to the US despite reserve managers' hesitance to invest in Treasuries since 2015. Should expectations of AI-fueled productivity gains falter, a significant retreat from both US stocks and debt could follow, markedly differing from past crises such as the 2008 financial meltdown, where heightened risk aversion usually propelled a flight into safe-haven assets.

Methodology: Analyzing Earnings Surprises

To understand the impact of big tech news on the markets, we established a daily shock series tied to the earnings announcements of the Magnificent 7 US tech companies. These firms now account for over a third of the S&P 500, embodying significant influence due to their advancements in AI. By focusing on narrow windows surrounding their earnings announcements, our analysis, adhering to event study methodology, facilitates a clearer understanding of how their earnings news correlates with wider productivity and the profitability of the broader index.

Our ‘Mag-7’ equity price shocks, outlined in Equation (1), represent the percentage change in share price surrounding earnings announcements, adjusting for the firms' weight in the S&P 500—this accounts for their rising market share from 3% to 35%. By measuring the changes between closing prices and the subsequent day's opening prices, we encapsulate responses even when multiple firms announce earnings concurrently.

Evidence from Mag-7 Earnings Shocks

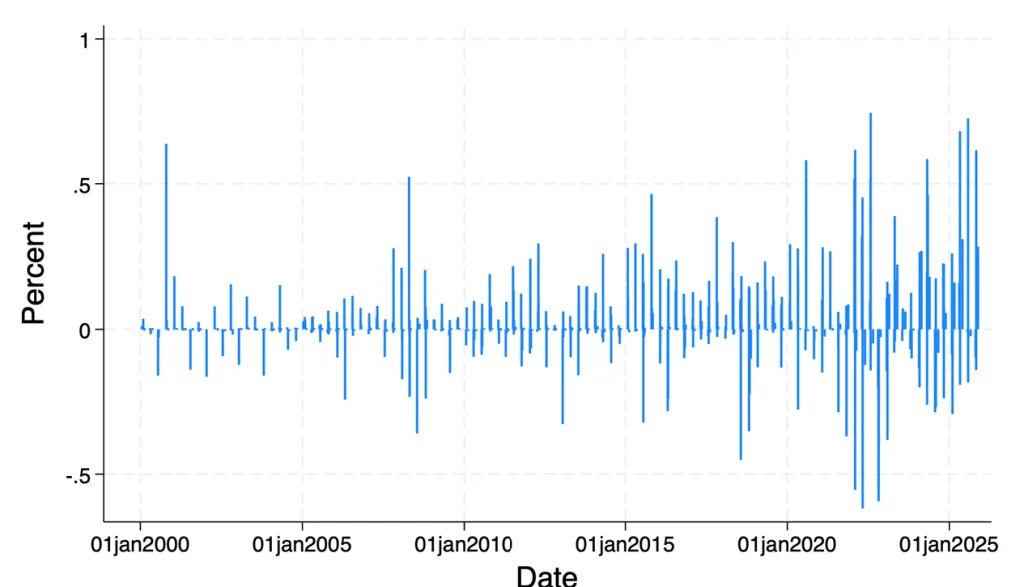
We focused on constructing a timeframe from 2000 to the end of 2025 to analyze Mag-7 equity price shocks. Our findings indicate that most shocks fell within -0.5% to 0.5%, with larger effects observed after 2020, correlating with the Mag-7's heightened presence in the S&P 500. The most significant decline recorded was on April 28, 2022, when Amazon reported Q1 earnings that fell short of expectations, leading to a 10% drop in share price post-announcement. This event catalyzed an approximate 4% decline in the S&P 500—despite Amazon holding only a 3% share of the index at the end of 2021. The market fallout extended beyond domestic markets, affecting UK equities, widening credit spreads, and causing the US dollar to weaken, underscoring the potential for systematic patterns that could characterize an AI market correction.
Analyzing Market Responses
Using our shock series, we investigated how surprises in big-tech equity prices affect global asset prices through a succinct local projection framework. The coefficients measured provide insights into the effects following a negative 1% Mag-7 equity price shock across various asset markets. The review included equity indices, effective exchange rates, credit spreads, nominal government bond yields, and breakeven inflation rates.
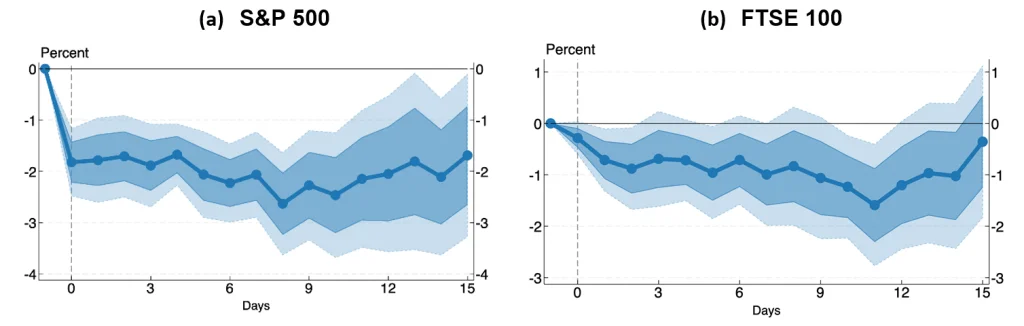
Equity markets are directly impacted as illustrated in Chart 2, which tracks the responses of the S&P 500 and the FTSE 100 to the negative shock. A negative 1% Mag-7 equity price shock results in the S&P 500 declining almost 2%. Additionally, within two days, the UK’s FTSE 100 dropped by 1%, despite showing no mechanical effect, illustrating significant responses in non-US equity indices.
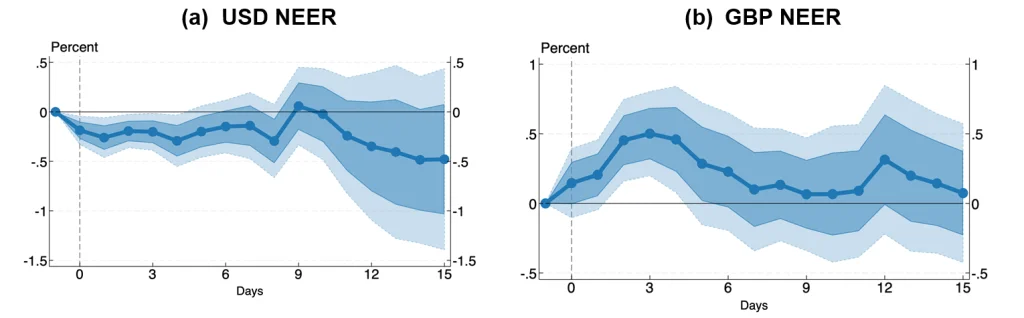
In terms of exchange rates demonstrated in Chart 3, the dollar depreciates immediately by up to 0.3% after a negative shock, while sterling appreciates roughly 0.5%. This depreciation of the dollar signals a shift among investors away from US equities towards foreign assets, hinting at potential downward revisions in future US productivity.
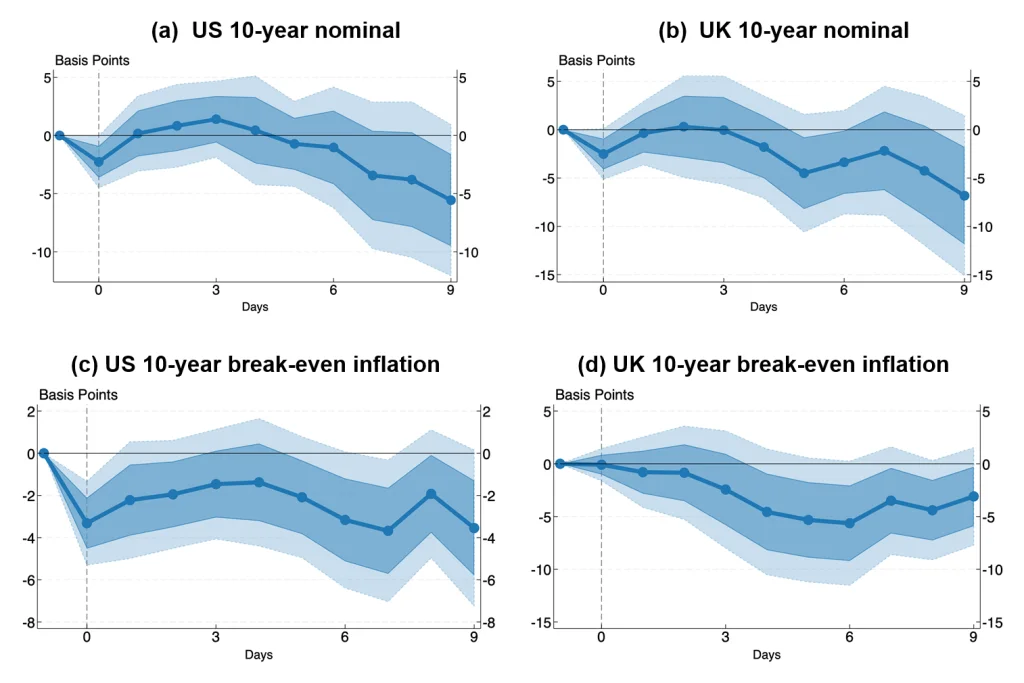
Chart 4 illustrates the effects on government bonds. Yields from both US and UK 10-year bonds experience immediate declines, signaling muted reactions to a flight-to-safety trend, with rebounds that remain statistically insignificant. However, following negative earnings news from the Mag-7, US breakeven inflation rates see a decline, implying shifts in demand dynamics.
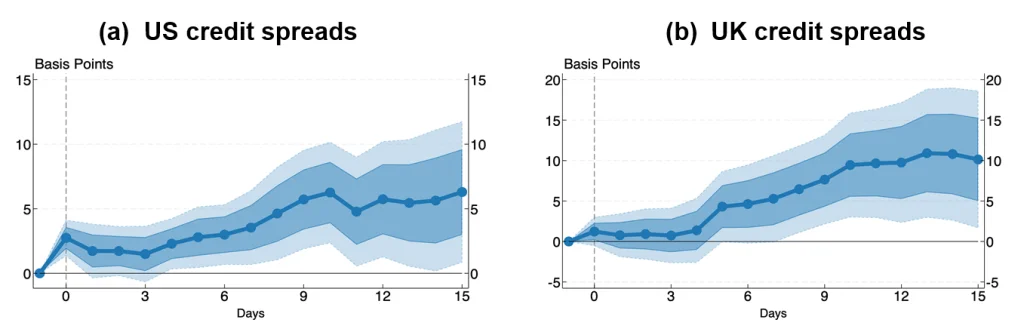
Lastly, corporate credit markets also reflect shifts following a negative Mag-7 earnings report. Chart 5 indicates that US credit spreads increase on impact, further elucidating how shocks in the big-tech sector can influence borrowing costs across the corporate landscape.
Concluding Insights
The surge in AI-centric equity valuations sparks expectations for enhanced US productivity growth. Our analysis of potential AI corrections through big-tech earnings shocks underscores how deeply interconnected global financial markets are. The ramifications of negative earnings in big tech extend far beyond the companies themselves, manifesting in weakened equity markets, heightened credit spreads, and a depreciating US dollar, which could heighten macroeconomic vulnerabilities worldwide.
Hence, policymakers should recognize that downturns in US tech valuations are unlikely to remain insulated; significant global financial repercussions may follow an AI market correction. Furthermore, if the dollar depreciates, it could intensify adverse macroeconomic impacts, altering the competitive landscape for foreign economies that typically leverage favorable currency conditions during times of financial distress.
Daniel Ostry, Roger Vicquéry, and Emilio Zaratiegui work in the Bank’s Global Analysis Division.
If you want to get in touch, please email us at [email protected] or leave a comment below.
Comments will only appear once approved by a moderator, and are only published where a full name is supplied. Bank Underground is a blog for Bank of England staff to share views that challenge or support prevailing policy orthodoxies. The views expressed here are those of the authors, and are not necessarily those of the Bank of England or its policy committees.