Aluminum Forecasts Indicate 2027 Surplus as New Supply Sources Emerge
Analysts predict aluminum will enter a surplus by 2027, driven by increased output from Indonesia and recovering Gulf smelters after recent disruptions.
Aluminum markets are preparing for a notable shift as forecasts suggest a surplus in supply by 2027, potentially exceeding 1 million metric tons. This shift is largely attributed to significant contributions expected from new production in Indonesia and a recovery in output from Gulf smelters, which have faced disruptions due to geopolitical tensions.
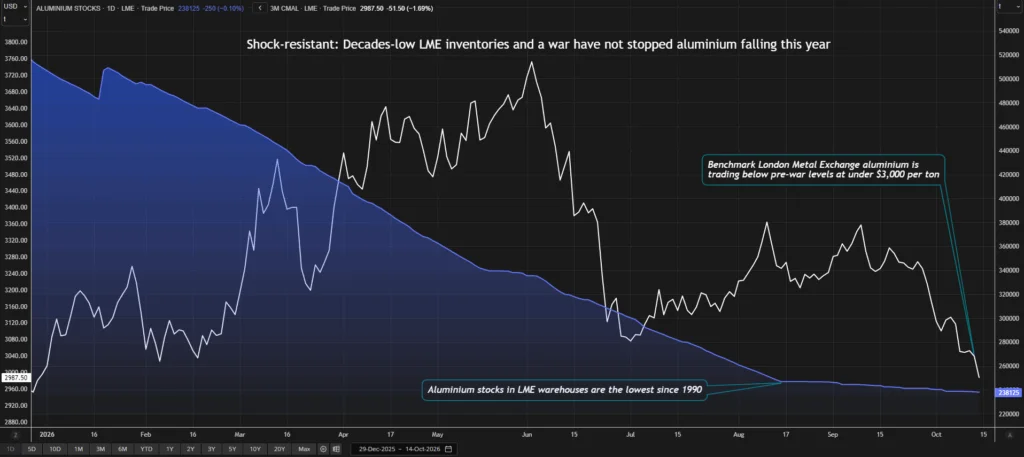
Recent market conditions have seen aluminum prices drop below $3,000 per ton, marking a decline to levels not observed since December. This fall comes after the metal's price surged to four-year highs in June, fueled by disruptions related to the conflict in Iran and a depletion of inventories. The bounce back from these disruptions is leading to a recalibration of market expectations.
Middle East Supply Recovery
Industry experts are anticipating a robust recovery in aluminum output from the Middle East. Ross Strachan, head of aluminum raw materials at CRU, stated, “We expect a substantial rebound in Middle East supply, with output rising to 6.4 million tons from 4.8 million tons this year.” This recovery is particularly significant given that the region accounts for about 9% of global primary aluminum capacity. Shipments from the area have been severely impacted by the ongoing conflict in Iran, which has strained supply chains.
According to CRU's analysis, the global aluminum market is projected to experience a shift from a deficit of 711,000 tons this year to a surplus of 1.4 million tons in 2024. This change comes on the back of enhanced production capabilities; last year, the world generated approximately 73.8 million tons of primary aluminum.
Indonesian Output and Infrastructure Challenges
Indonesia is also poised to play a pivotal role in the growth of aluminum production, especially with projects spearheaded by Chinese investors. CRU forecasts that Indonesian output will more than double by 2027, reaching 3.2 million tons. This growth is critical as Chinese companies turn to Indonesia for expansion due to capacity limits in their domestic markets. Uday Patel, a senior research manager at Wood Mackenzie, echoed similar sentiments but cautioned that the anticipated surplus could be around 500,000 tons next year, as opposed to the more optimistic forecasts. Patel highlighted a looming challenge: "The smelters are being built quicker than the infrastructure," indicating that ports and power supply networks are struggling to keep pace with rapid production expansion.
Logistical and Market Considerations
Despite the increased production forecasts, logistical challenges persist for Gulf smelters. While the recovery of output is encouraging, smelters are now compelled to seek alternative shipping routes, which come with escalated transportation costs as they avoid the Strait of Hormuz. This situation exemplifies how external factors can hinder the benefits of increased supply and keep premiums elevated. Patel noted, “You could see a situation where you have a surplus but still elevated premiums and potentially prices.”
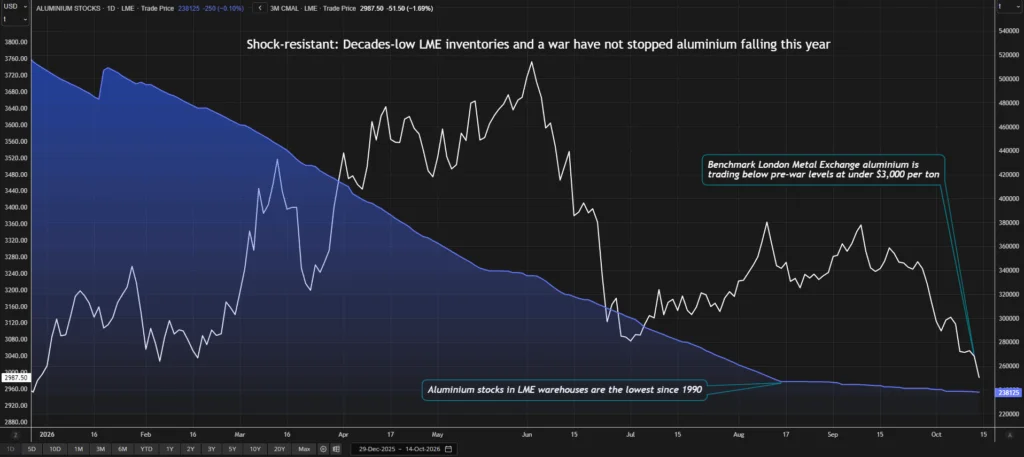
Current estimates suggest Indonesia might only produce around 1.2 million tons of aluminum this year, far below earlier projections exceeding 2 million tons. Michael Widmer, a commodity strategist at Bank of America, suggests that the anticipated ramp-up in aluminum production in Indonesia will be gradual, projecting 2.2 million tons for the following year, primarily concentrated in the latter half of the year. This indicates a growing awareness among analysts that while the supply is on the horizon, it might not arrive as quickly as initially believed.
With increasing production from both established and emerging supply regions, stakeholders in the aluminum market must navigate this complex landscape of fluctuating prices and infrastructural challenges. Investors, suppliers, and manufacturers alike need to keep an eye on these dynamics, which could reshape the outlook for aluminum well into the latter part of the decade. As companies adjust their strategies and production plans, understanding the nuances of global supply trends will be essential for making informed decisions in this volatile environment.