Chile's Copper Supply Faces Mounting Disruptions Amid Severe Weather and Labor Issues
Chile, the world's largest copper producer, grapples with rising supply risks due to severe weather, labor unrest, and geological challenges at major mines.
A recent snow avalanche at Codelco’s El Teniente mine has intensified supply concerns in Chile, the leading global producer of copper. This incident, coupled with extreme weather patterns and ongoing labor disputes, poses significant risks to copper output across the nation.
The El Teniente mine, renowned as the world’s largest underground copper mine, is a critical operation for Codelco and a major contributor to Chile's copper supply. While the mine's open-pit operations remain suspended, underground and processing facilities continue to function. Located about 75 kilometers southeast of Santiago in the Andes, El Teniente's disruptions come at a precarious time as forecasts suggest a potentially intense El Niño weather event could strike in 2026-27, raising concerns for future output.
Increasing Production Vulnerabilities
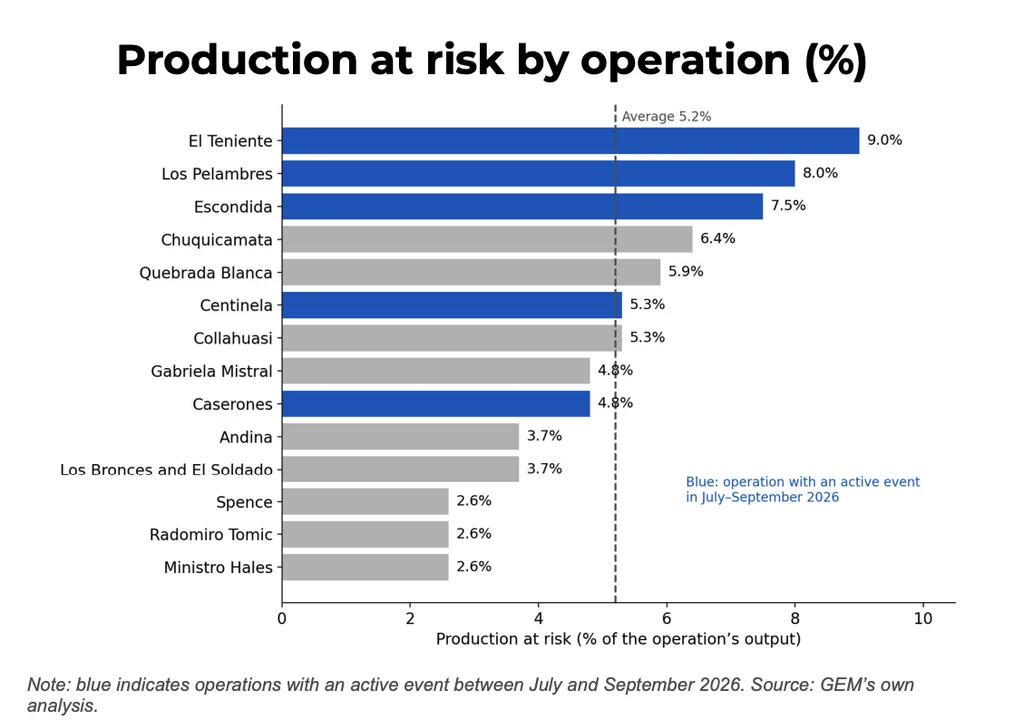
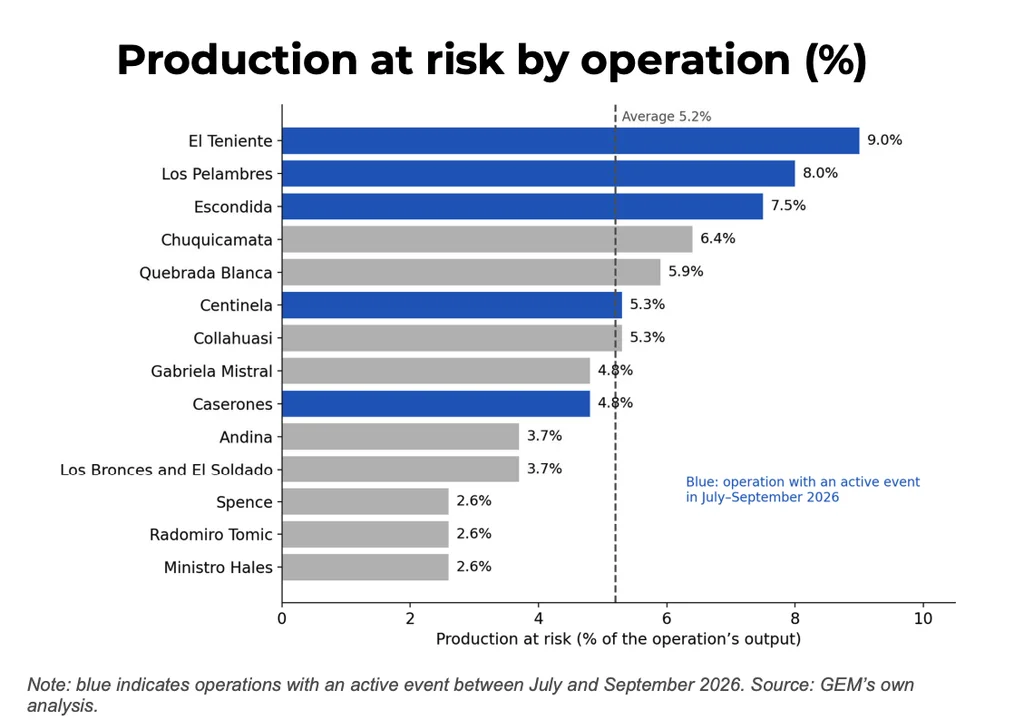
A study conducted by GEM Mining Consulting earlier this month highlighted vulnerabilities across Chilean copper mines, estimating that an average of 5.2% of production is threatened by strikes, extreme weather, geological challenges, and accidents. The study evaluated 14 significant copper operations, assigning a "Production-at-Risk Index" that indicates the level of risk faced by each mine based on various threats. Notably, El Teniente scored the highest at 9%, with Los Pelambres at 8% and Escondida at 7.5%. Furthermore, nine operations were identified as having at least one threat categorized as high.
This overview underscores the pressing challenges confronting mines that collectively represent a substantial portion of global copper supply, especially as the operation faces potential disruptions from an anticipated historically significant El Niño phenomenon.
Recent storms have already impacted operations at key mines like Los Pelambres and Caserones, illustrating the immediate implications of severe weather conditions on the industry. Such extreme weather events can lead to prolonged interruptions, which are critical, given the increasing global demand for copper.
In addition to weather-related risks, El Teniente is experiencing complications from geological issues, most notably under its Andes Norte project. Codelco has suspended this project due to deep seismic risks, obstructing plans to develop new areas for production and further impeding the mine's output capabilities.
Labor Disputes Complicate Operations
Labor unrest compounds the operational uncertainties within the sector. Recently, a week-long strike at Antofagasta's Centinela copper mine, one of the company's four Chilean operations, drew attention as two unions engaged in negotiations with the company for resolution. This strike is particularly noteworthy as it marks only the second stoppage in the mine's history, with Centinela having produced 240,400 metric tons of copper last year.
At the same time, supervisors at BHP’s Escondida, which is dubbed the largest copper mine worldwide, are currently involved in government-mediated negotiations in a bid to prevent a strike. This mine recently faced a tragic incident that temporarily halted operations, further complicating its output and operational stability.
Market Reactions and Future Outlook
Despite the increasing list of operational challenges, investment bank Panmure Liberum noted that the actual production losses may not align with the prevailing copper price levels. Recent disruptions occurring in 2025-26, which include incidents at Indonesia's Grasberg mine and the Kamoa-Kakula operation in the Democratic Republic of Congo, account for an estimated 350,000 to 400,000 tonnes of contained copper annually.
This represents only 30% to 50% of the overall disruption allowances currently considered in the market, implying that actual losses are significantly lower than what investors are anticipating. As Panmure Liberum stated, the prevailing copper prices seem to be largely driven by speculative and financial factors rather than actual production interruptions.
This analysis suggests that while on-the-ground operational challenges are escalating, the broader market has not yet accounted for disruptions that could match investor expectations. Thus, the fluctuations in copper prices could remain vulnerable to shifts in market sentiment, especially in light of the continuing threat of weather-related interruptions and unresolved labor issues that could hinder operations further.
Monitoring future developments will be critical, as both labor negotiations and weather forecasts could drastically influence the supply side of the copper market, significantly impacting global prices and accessibility for various industrial applications.