Copper and Nickel Prices Expected to Double by 2035 Amid Supply Constraints
A Coface report forecasts copper and nickel prices could double by 2035 due to rising demand and persistent supply limitations, projecting significant deficits.
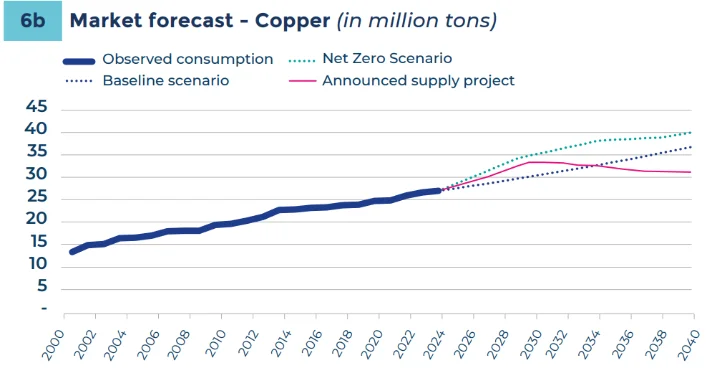
Copper and nickel prices could potentially double over the next decade, fueled by increasing demands from construction, the energy transition, and widespread electrification, according to a report from global financial services firm Coface. The analysis highlights an environment where supply is struggling to match this demand, leading to potential price surges in the coming years.
Significantly, aluminum, copper, and nickel might experience average supply deficits of around 10% of demand by 2035. This projection is underpinned by a complex interplay of production limitations and escalating consumption levels. Coface’s findings emanate from comprehensive data analysis drawn from several reputable sources, including the London Metal Exchange, U.S. Geological Survey, World Bank, and the International Energy Agency (IEA).
Shifts in Metals Trade
Marcos Carias, North America economist at Coface, emphasizes that U.S. tariffs are part of a larger trend in metals trading, reflecting a multi-year evolution where governments increasingly restrict trade. Such tariffs exacerbate current supply issues, creating additional pressure as demand outstrips availability.
The projected supply deficits could herald a prolonged bullish phase for industrial metals, driven by expanding markets for clean-energy technologies, electric vehicles (EVs), battery storage, and the infrastructure necessary for increased grid capacity. Unlike typical commodity cycles that may fluctuate from year to year, the current situation illustrates structural constraints that could undermine quick resolves—even if prices increase substantially.
Supply Constraints
Over the next decade, supply growth estimates are starkly low: an annual increase of just 1% for copper, 1.5% for nickel, and only 0.4% for aluminum is anticipated. In contrast, demand is expected to rise by approximately 1.8% annually across these metals. In scenarios targeting net-zero emissions, demand growth surges to around 2.2% for copper and aluminum, and an impressive 4.5% for nickel, driven largely by green technology deployment.
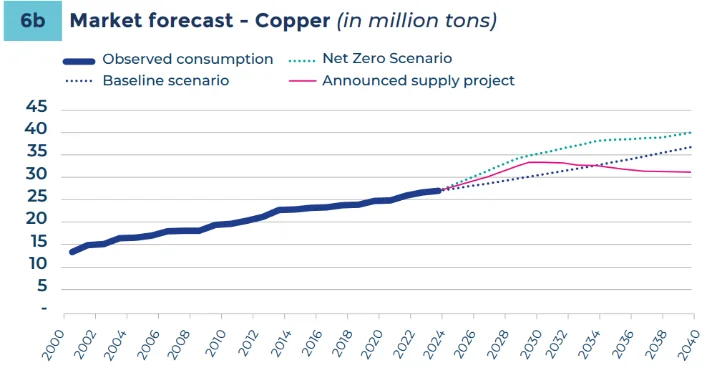
The report highlights that the growing demand from the electrification sector—particularly through EVs and data centers—exposes weaknesses within the supply chain, with mining operations unable to keep pace. Even though price shifts are often viewed cyclically, the deeper structural changes in both demand and supply characterizing metal markets suggest the emergence of a new bull market.
Permitting delays are a significant roadblock for mining projects, extending timelines for production to start and ultimately affecting the supply chain. Coface noted that trade restrictions have surged significantly, with 1,138 import and export limitations currently enforced—more than tripling from 357 just a decade ago. The recent U.S. tariff measures further tighten market access and reflect a long-term shift manufacturers need to recognize.
Carias stated, “For manufacturers in the U.S., Canada, and Mexico, that means planning for higher metal costs over the long term instead of waiting for a trade deal to bring prices back down.” Factors such as unpredictable exploration outcomes, increasing processing times that range from 15 to 20 years, and limited incentives for expanding mining capacity are perpetuating a structural compression of ore supply, according to the analysis.
Projected Deficits
The ongoing energy transition amplifies existing structural tensions as low-carbon technologies consume an increasing share of metals. By 2035, clean-energy technologies could represent roughly 35% of global copper and nickel consumption.
Coface forecasts that copper might encounter a shortfall of up to 17%. The refined copper deficit could expand from 1.5 million tons currently to as much as 6.5 million tons by 2035, equating to about 11% of projected demand. In a net-zero emissions scenario, the shortfall could heighten to an estimated 17%. Moreover, refined nickel could witness a deficit approaching 35% of projected consumption, largely due to the burgeoning battery manufacturing sector.
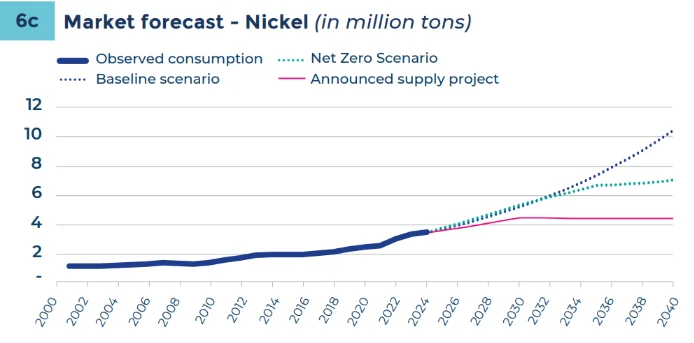
In addition, projections indicate an aluminum deficit ranging from 5 to 15 million tons—or around 10% of anticipated demand. However, this shortfall will stem more from industrial and energy constraints rather than a lack of raw materials.
Typically, when supply constraints are due to production costs or investment challenges, higher market prices tend to stimulate additional production capacity, fostering eventual market rebalancing. However, when constraints arise from raw material availability, increased prices may fail to trigger the necessary supply influx, which could result in persistent price pressures, as indicated in the report.
With structural factors firmly entrenched within the metals market, stakeholders should prepare for a landscape iterated by ongoing changes in demand, regulatory environments, and supply constraints—all factors that could shape market dynamics for years to come.