Evaluating Forbearance Lending: Insights from Japan's SME Financing Facilitation Act
Research shows Japan's loan forbearance scheme can aid struggling businesses without fostering "zombie" firms, challenging common critiques of such interventions.
Understanding Loan Forbearance in Crisis Management
Interventions in corporate credit markets have become a key part of policy responses during crises over the past two decades. Among these measures, loan forbearance stands out as a mechanism through which lenders and regulators provide temporary relief to struggling borrowers. Typically, the literature is critical of loan forbearance, particularly within the corporate sector, highlighting its potential to foster 'zombification'—a scenario where banks continue to support unproductive firms, ultimately dragging down overall productivity. However, recent findings from new research indicate that when forbearance lending is paired with business restructuring plans, it can effectively provide temporary relief to firms while safeguarding both employment and output without contributing to the zombification of the corporate landscape.
The Japanese SME Financing Facilitation Act: A Unique Case Study
This research focuses on the Japanese SME Financing Facilitation Act of 2009, which offers a distinct quasi-experimental framework to analyze corporate forbearance. Under this legislation, banks were mandated to extend forbearance to SMEs that met specified criteria, effectively removing discretion from the lenders. Additionally, this act allowed financial institutions to exclude restructured loans from their non-performing loans metrics, provided that a credible business restructuring plan was in place to restore loan performance within five years. The results demonstrated almost universal compliance from banks in granting forbearance, influenced by informal pressures from the government.
Evaluating the Policy Framework
The evaluation of this policy involves a systematic approach driven by a four-step analysis. First, a search and matching model of the credit market reveals that banks are incentivized to forbear. Second, the research harnesses firm-level data from Tokyo Shoko Research (TSR) to assess how interest rates were affected by the policy using a difference-in-differences (DiD) method. This involved constructing a measure of firm-level exposure to the program employing survey data from the Research Institute of Economy, Trade and Industry (RIETI). Third, by utilizing the model and annual treatment effect estimates on interest rates, the research conducts hypothetical scenarios (counterfactual exercises) that gauge potential impacts on capital stock and productivity had the policy not been enacted. Finally, a further investigation into the creation of zombie firms is conducted using a DiD framework.
Impact of Forbearance on Credit Rates
Chart 1 illustrates the estimated impacts of the SME Financing Facilitation Act on average loan interest rates. The analysis found no significant effects on loan interest rates prior to the enactment of the law. However, from 2010 onward, the Act acted as a substantial interest rate subsidy, decreasing average loan rates by an estimated 18.5% for qualifying firms between 2010 and 2018. The most pronounced subsidies were noted shortly after the implementation of the law, with effects diminishing over time, turning positive by 2017. This trend signifies a decrease in the incentives for forbearance as temporary payment deferrals became predominant rather than outright debt forgiveness.
Credit Subsidies and Aggregate Capital Stock
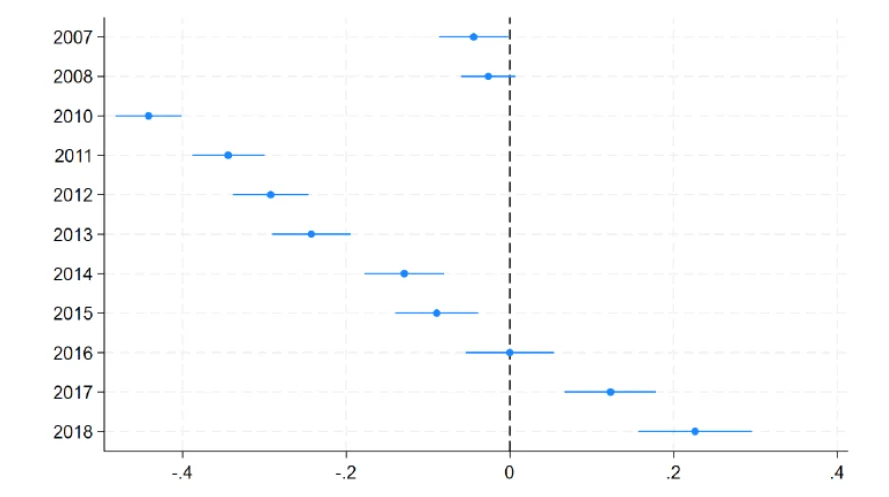
Table A demonstrates the counterfactual analysis, correlating credit availability with productivity metrics. Findings indicate that while the act boosted the aggregate capital stock, it simultaneously lowered productivity levels. On average, the policy increased the capital stock by 1.4% but reduced capital productivity by 0.5%. Two potential scenarios were analyzed concerning capital released from these firms: one where capital remained unallocated and another where it was reallocated to more productive firms. The former scenario predicted an output increase of 2.5%, whereas the latter suggested a decrease of 1.5%, underscoring the notion that capital reallocation is typically pro-cyclical during economic downturns and hence, more unstable.
Examining the Creation of Zombie Firms
The study also scrutinizes the concern that the forbearance measures could lead to an increase in zombie firms—essentially businesses that are unable to sustain themselves but continue to receive financial support. The analysis showed that the policy improved interest coverage ratios (ICRs) by reducing debt servicing pressures and decreased bankruptcy probabilities, ultimately yielding improved total factor productivity (TFP) rates. Remarkably, the findings suggest that the act not only avoided contributing to the zombification of firms but also facilitated their recovery through mandated restructuring plans.
Key Policy Insights
This research yields vital insights that question the prevailing notions about the detrimental effects of loan forbearance. Specifically, it emphasizes that when strategically combined with business restructuring plans, forbearance can serve as a functional tool for sustaining firms that are temporarily distressed but essentially viable. This assertion posits that a well-structured forbearance policy can mitigate adverse productivity impacts during acute economic stress, thereby acting as a constructive element in crisis management frameworks for the corporate sector.
As the study illustrates, the interplay between forbearance and firm restructuring sustains critical economic activity during downturns while helping prevent long-term productivity losses. This suggests a nuanced approach to crisis management in the financial sector, endorsing careful planning and execution of forbearance linked with strategic operational reforms.
Isabelle Roland works in the Bank’s Macro-Financial Risks Division, Yukiko Saito works in the Faculty of Political Science and Economics, Waseda University, Tokyo, and Philip Schnattinger works in the Bank’s Structural Economics Division.
For further engagement, feel free to reach out via email.