Understanding Yield Curve Dynamics: The Impact of Monetary Policy Shocks
This article examines how UK monetary policy influences the yield curve, emphasizing the distinct macroeconomic effects of level and slope shocks on inflation and growth.
Sofia Carollo and Natalie Burr
Monetary policy primarily influences short-term interest rates through the Bank Rate set by the Monetary Policy Committee (MPC), but its effects cascade through various borrowing costs experienced by households and firms across different time horizons. These borrowing costs, including deposit and mortgage rates, are significantly influenced by the entire shape of the yield curve rather than a single rate. Analyzing how monetary policy announcements reshape the yield curve reveals crucial insights into inflationary impacts and economic dynamics.
The Importance of the Full Yield Curve
The MPC may set an overnight policy rate, but this rate does not reflect what households and companies actually pay. In practice, they deal with various rates that extend from short-term loans to long-term mortgages. This disconnect means that assessing monetary policy's effectiveness requires looking beyond the policy rate and analyzing movements across the entire yield curve. When the Bank Rate changes, it affects the short end of the yield curve directly but can influence longer rates through various channels, including market expectations regarding economic conditions and future monetary policy.
Policymakers utilize a mix of tools, such as quantitative easing and forward guidance, to manage yield perceptions actively. Nevertheless, external factors—ranging from anticipated economic performance to shifts in fiscal policy and risk premiums—also play significant roles in shaping the yield curve's level and slope.
Separating Level and Slope Effects
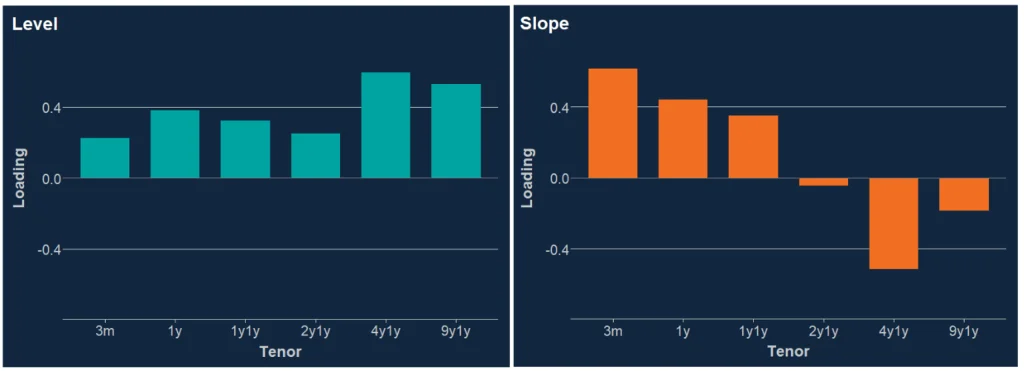
To understand how monetary policy impacts the economy, it's essential to differentiate between level and slope changes within the yield curve. A level change represents a near parallel shift across rates, while a slope change indicates shifts in the steepness of the curve at various maturities. These channels lead to distinct economic outcomes, making it necessary to decompose policy impacts in these ways.
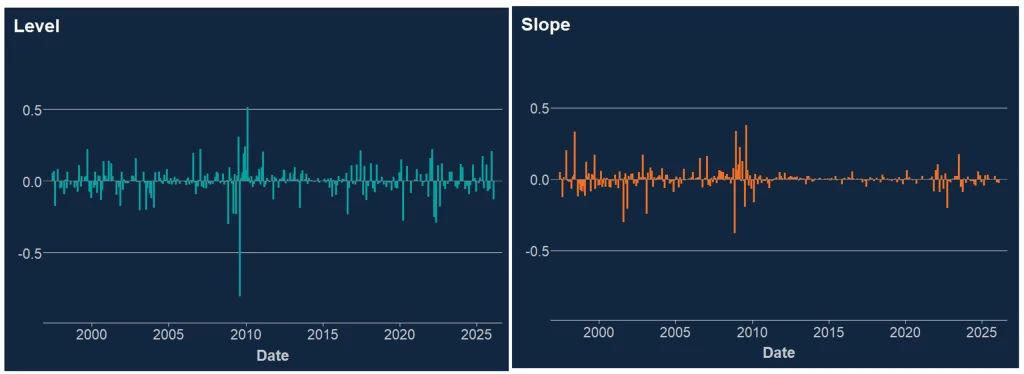
In the analysis, the authors rely on a combination of spot and forward rates, including 3-month and 1-year spot rates, and a set of forward rates across different time horizons. They chose to examine UK monetary policy effects from 1997 onwards surrounding MPC announcements, enabling a high-frequency evaluation of yield movement in narrow windows. This approach enhances the accuracy of attributing yield movements specifically to monetary policy shifts rather than unrelated news or events.
Tracing Policy Impacts through Statistical Analysis
Using principal component analysis (PCA), the authors successfully isolate the common yield movements following monetary policy announcements. The first component generally captures the level effect on the yield curve, while the second reflects the slope effect. By fitting these components to empirical data, they create a series of level and slope surprises that serve as proxies for monetary shocks, which is critical for assessing their macroeconomic implications.
Macroeconomic Consequences of Level and Slope Shocks
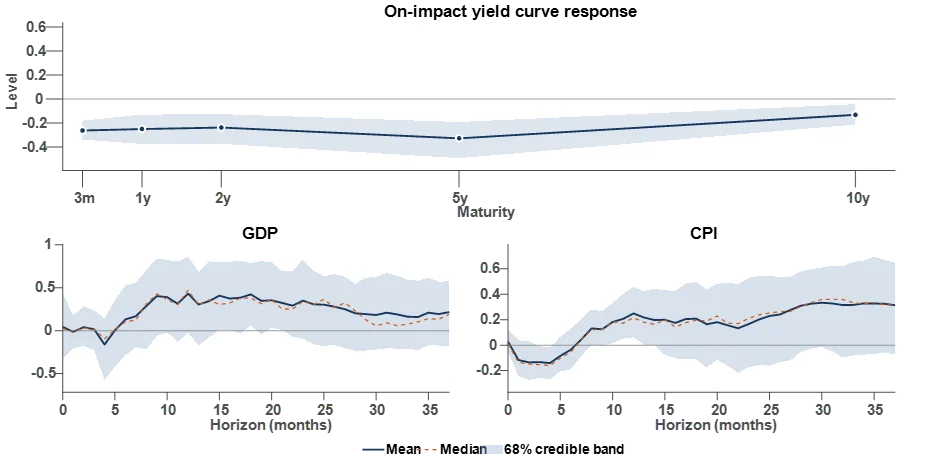
The next step involves determining how each type of shock affects key economic indicators like GDP and CPI. To do this, the authors employed a Bayesian vector autoregression (BVAR) model that includes variables such as UK asset prices and levels of real GDP and CPI. The analysis encompasses a period stretching from June 1997 to December 2019, examining the lags of reactions to shocks across various maturities.
An important finding is that a negative level shock—specifically a 25-basis-point reduction in the 1-year yield—creates widespread declines in yields and lower credit spreads, ultimately enhancing equity prices and depreciating the currency. Such movements lead to an easing of overall financial conditions, spurring economic activity and influencing inflation dynamics. The economic output begins to increase gradually following this shock, with noticeable inflationary responses emerging later, consistent with traditional economic theories regarding delayed reactions in price levels.
Contrasting Effects of Slope Shocks
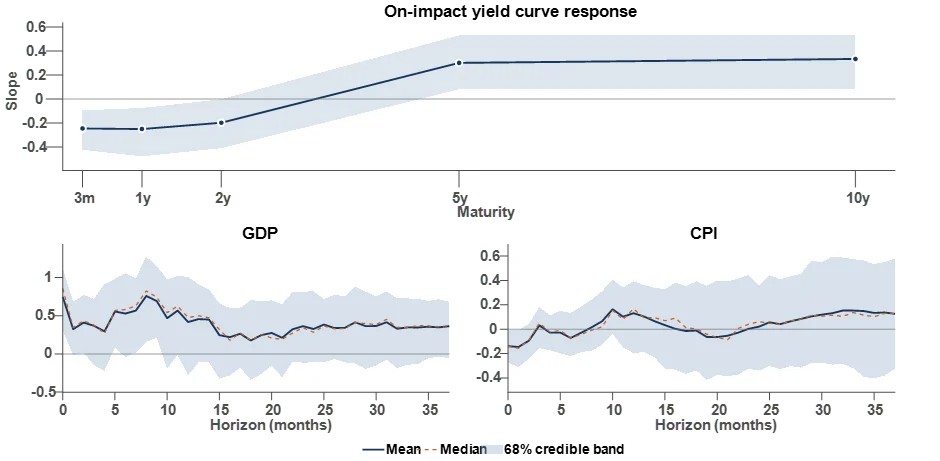
In comparison, a negative slope shock, resulting in reduced short-term yields while simultaneously tightening longer-term rates, tends to assist GDP growth without significantly impacting the inflation rate. The initial stimulus appears to derive from reduced borrowing costs on shorter loans, promoting economic activity immediately. However, the lasting effects on prices seem muted, suggesting a more complex interaction where both short and long-term rate adjustments influence different areas of the economy.
Policy Implications and Recommendations
The findings underscore the various channels through which monetary policy can impact economic dynamics. The analysis reveals that the effects of monetary policy decisions extend far beyond mere changes in a single interest rate; rather, they hinge upon understanding the yield curve's structure—its level and slope. Shifts across maturities carry unique economic repercussions, affecting the potency and timing of monetary transmission.
This means that while the MPC cannot control every aspect of the yield curve, it can strategize better by focusing on how changes are distributed across different maturities. For policymakers, recognizing that the timing and strength of monetary impacts vary significantly based on these configurations is essential to gauge economic transmission effectively.
Ultimately, distinguishing between level and slope shocks captures the multifaceted behaviors of financial markets and economic indicators, guiding decisions that may significantly influence both short-term growth and long-term stability.
Sofia Carollo and Natalie Burr contribute their expertise from the Bank's Monetary and Financial Conditions Division and External MPC Unit, respectively.
If you wish to engage in further discussion or provide feedback, feel free to reach out via [email protected] or leave comments below.