Understanding the Dynamics of Interest Rate Swaps in Today’s Financial Markets
This article explores the intricacies of interest rate swaps, highlighting sector participation, trading behaviors, and their impact on asset pricing in the current environment.
Interest Rate Risk: A Threat to Financial Stability
Both the 2023 collapse of Silicon Valley Bank and the 2022 crisis among UK pension funds underline a critical issue in finance: interest rate risk. Various sectors, particularly those with mismatches between short-term cash flows and long-term liabilities, face vulnerabilities to sudden shifts in interest rates. Notably, pension funds and insurers possess short-term liquidity needs while holding long-term obligations, complicating their financial management. Banks tend to follow a strategy of lending long and borrowing short. Interest rate derivatives, especially interest rate swaps, provide tools for these entities to manage their exposure, yet research on this market remains limited. This creates gaps in understanding risk-sharing dynamics and the consequences stemming from imbalances.
Constructing the Data Set
Recent research involved creating a comprehensive dataset on interest rate swaps from confidential Bank of England data. This analysis reveals how various investors utilize these instruments and the factors influencing swap pricing. It highlights persistent demand imbalances across sectors, the identification of natural counterparties, and the pivotal role of dealers in facilitating these transactions.
The Importance of the Interest Rate Swap Market
With rising interest rates and recent market disruptions, the distribution of interest rate risk has garnered closer scrutiny. The implications extend beyond large institutions like banks and pension funds to include smaller entities such as individual mortgage holders and small businesses. On one hand, derivatives can offer necessary hedging mechanisms for companies inherently facing interest rate risk; on the other, they can be tools for speculative trading aimed at profiting from anticipated interest rate movements.
Understanding Interest Rate Swaps
One prevalent method for hedging or speculating on interest rate risk involves entering interest rate swap agreements (IRS). In a typical IRS, a company swaps fixed-rate payments for variable ones based on an underlying benchmark, such as SOFR or SONIA. The cash flows in swaps are calculated based on a notional amount and can extend for maturities exceeding 50 years. The net notional position serves as a measure of exposure, representing the difference between fixed-rate receivables and payables.
Sector-Specific Hedging Needs
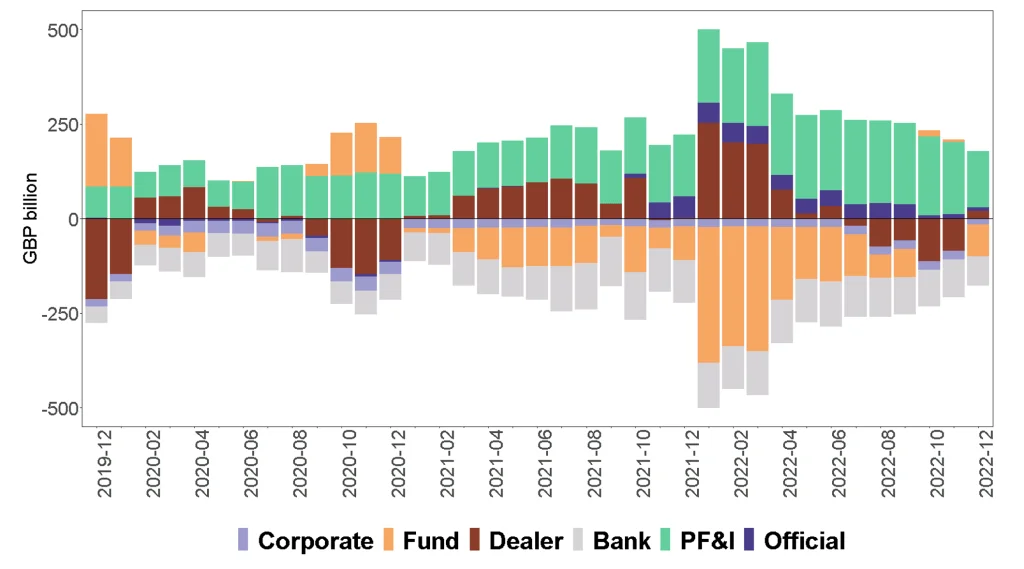
Different sectors exhibit unique behaviors when managing interest rate risk based on their business models. For instance, pension funds, which are obligated to provide fixed income to policyholders, typically seek to receive fixed positions to safeguard against rate fluctuations. Conversely, banks may pursue a strategy of paying fixed rates to align their liabilities with assets, thereby shortening duration. This complementary relationship allows for mutual benefit in the swaps market.
Sector Participation and Positions in the Swap Market
The analysis identifies four primary end-user segments in the swaps market: funds (including hedge funds), pension and liability-driven investment funds, banks, and corporations. Each sector's positions align with its balance sheet demands; pension funds are generally net receivers of fixed payments, while banks and corporations usually pay fixed rates, reflecting their respective hedging strategies. This alignment offers a risk-sharing dynamic across these markets.
Maturity Preferences in Swaps
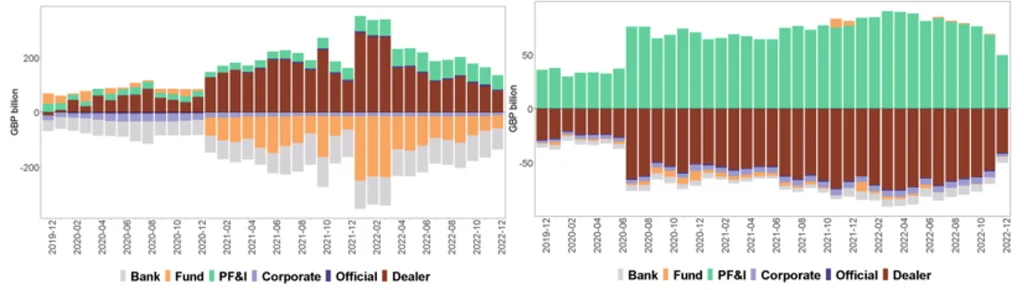
Analyzing market segmentation by maturity reveals significant trends: pension funds and insurers mostly engage in long-term swaps (10 years and above), while banks focus on short to intermediate maturities (three months to five years). This behavior supports the preferred habitat investor hypothesis, suggesting that different investors are attracted to varying maturities based on their asset-liability durations.
Response to Interest Rate Changes
Different sectors adapt their net positions in response to shifts in interest rates. Research shows that pension funds tend to increase their net receive positions when rates decline, whereas banks and corporations typically increase net pay positions during the same scenario. This dynamic again illustrates the complementary nature of participating sectors within the swaps arena.
Dealer Imbalances and Market Stability
Dealers in the swaps market often find themselves in imbalanced positions, generally receiving fixed rates on short maturities while paying on long maturities. This results in net negative duration, accentuating their role as market intermediaries necessary for stability. Understanding these dynamics is crucial for evaluating overall market health and resilience.
Implications for Asset Pricing
The swap spread—the difference between swap rates and similar maturity bond yields—serves as a critical indicator of perceived risk in the market. Research indicates the existence and persistence of negative swap spreads can be traced back to significant imbalances absorbed by dealers in response to sector demand for swaps.
Demand Pressures and Their Effects
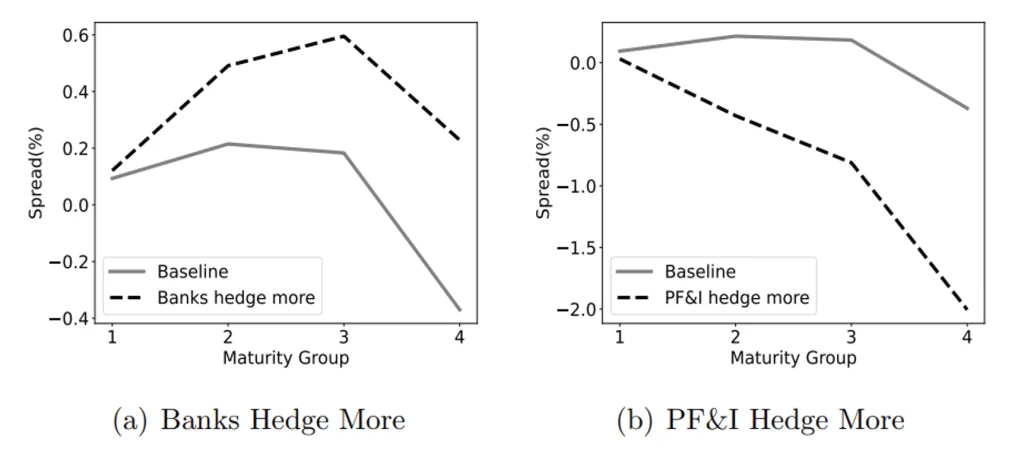
Our calibration findings suggest that demand pressures, particularly from sectors dealing in both short-to-intermediate and long maturities, significantly influence swap spreads. For instance, if banks increase their hedging demand, it may lead to higher long-term swap spreads, impacting the cost structure for pension funds and liability-driven investment funds. The pressures can be triggered by regulatory changes or abrupt market events, such as the Silicon Valley Bank incident, highlighting the interconnected nature of these economic factors.
Conclusion
This study illuminates the complexities of risk sharing in the interest rate swap market and its implications for asset pricing. By leveraging detailed datasets from the Bank of England, we unveil how varying sectors interact within the swaps market and the resulting asset pricing phenomena. The significance of dealer behavior in facilitating risk transfer and the effects of sector-specific shocks on swap spreads are paramount for both policymakers and market participants seeking to navigate these turbulent waters.