Assessing the Liquidity of SONIA Futures in UK Interest Rate Markets
Liquidity in SONIA futures has improved since the transition from LIBOR, yet vulnerabilities remain. Key data release timings may impact market participation.
David Glanville and Arif Merali
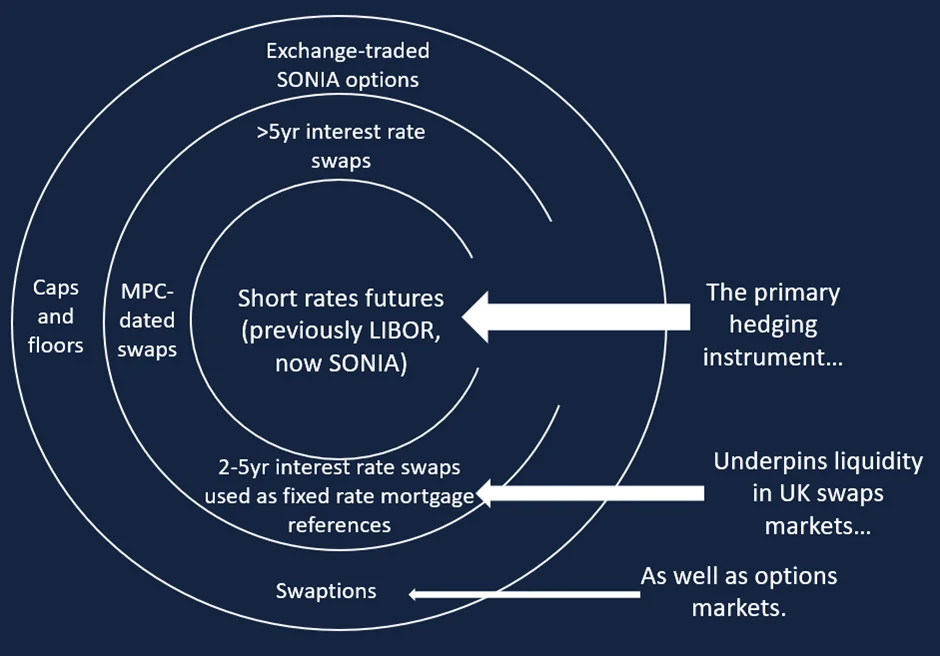

Short-term interest rate (STIR) futures form the backbone of interest rate markets, crucial for pricing expectations surrounding central bank policy rates. They support various UK rate derivatives, including swaps and options, playing a vital role in both monetary policy transmission and interest rate risk hedging necessary for financial stability. However, liquidity in the UK’s STIR futures market faced notable challenges in 2022 amidst rising volatility. Although metrics like open interest and trading volumes have seen improvements as market stability returned, ongoing concerns about market depth linger, indicating room for further enhancements.
To address liquidity further, a potential reversion to publishing key economic data during market hours could significantly bolster market resilience and depth.
Understanding SONIA Futures
SONIA, or Sterling Overnight Index Average, serves as the primary risk-free interest rate benchmark in the UK following the transition from the controversial LIBOR index at the end of 2021. SONIA futures are specific contracts within the STIR derivatives category that allow market participants to manage interest rate exposure or speculate on SONIA movements, which closely track the Bank of England's Bank Rate. These futures underpin a vast array of interest rate derivatives, integral to banks and building societies when structuring fixed-term mortgages. Market-makers often utilize SONIA futures to hedge their own risks; if these futures are illiquid, it complicates risk management, potentially leading to higher mortgage costs for consumers.
Impact on Monetary Policy
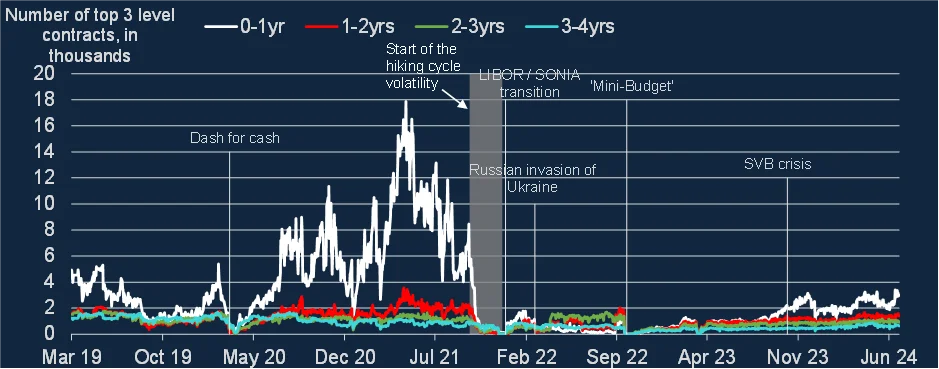
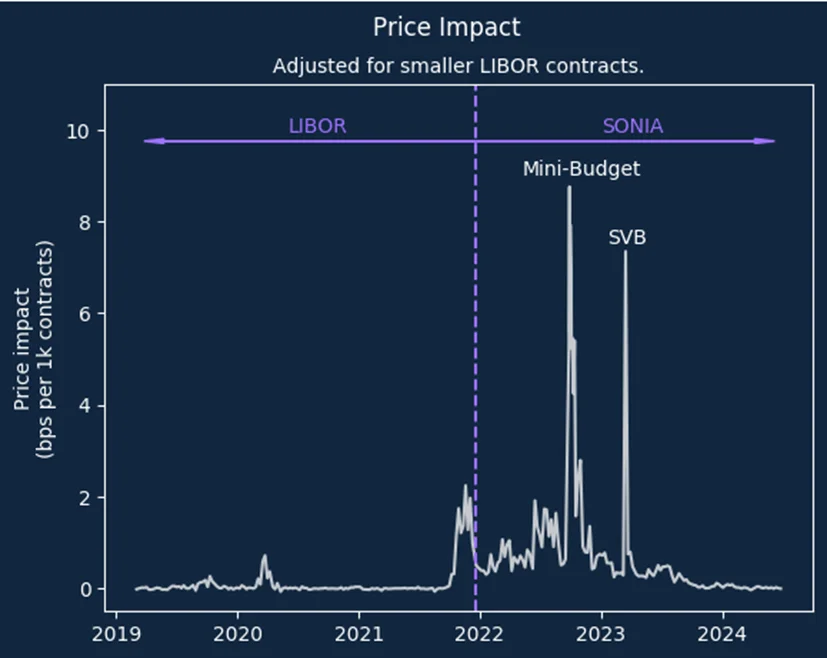
The significance of SONIA futures extends beyond mere pricing for derivatives; they are pivotal for effective monetary policy transmission. A robust and fluid SONIA futures market enables a more accurate reflection of market participants' expectations regarding future Bank Rate settings. Past events, such as the 2022 'Mini-Budget' turmoil and the 2020 'dash-for-cash' situation, illustrate instances when SONIA futures became misaligned with fundamental economic assessments, largely attributed to liquidity constraints. According to the Bank of England's Market Participants Survey during the Mini-Budget, a substantial portion of the divergence observed between market pricing and expectations stemmed from this very illiquidity and surrounding technical factors.
SONIA Futures and Financial Stability
Derivative instruments like SONIA futures are instrumental for banks and non-bank financial entities in managing interest rate risk. A liquid derivatives market facilitates efficient risk transfer, fostering overall financial system stability. The interconnected nature of different derivatives markets increases systemic risk, particularly during periods of heightened tension. Moreover, algorithmic traders are key liquidity providers in the SONIA futures market. While these algorithms can quickly boost trading volumes under stable conditions, they may significantly withdraw from the market in times of uncertainty, exacerbating liquidity shortages in volatile environments.
Current State of Liquidity in SONIA Futures
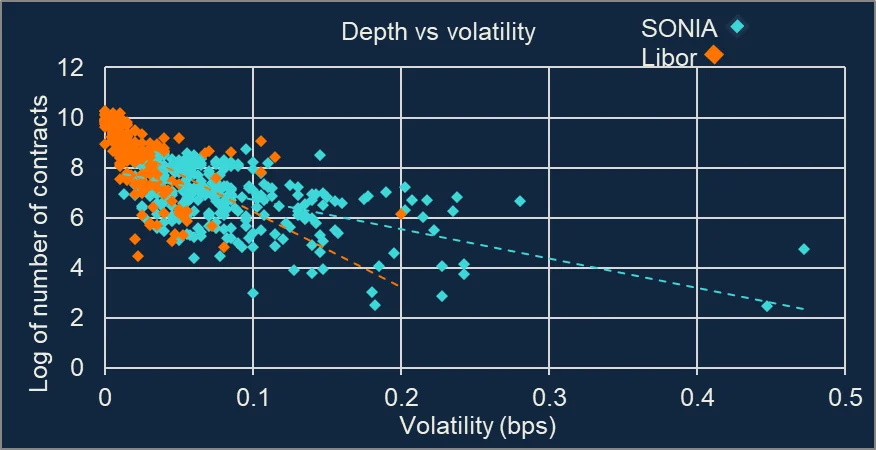
Since the interest rate hikes began in late 2021, the liquidity metrics for SONIA futures—such as market depth, open interest, and trading volume—initially deteriorated and persisted throughout much of 2022.
Comparatively, US STIR futures did not experience a similar decline in liquidity during their transition, suggesting that the UK market may be influenced by unique systemic challenges.
Assessing Underlying Illiquidity
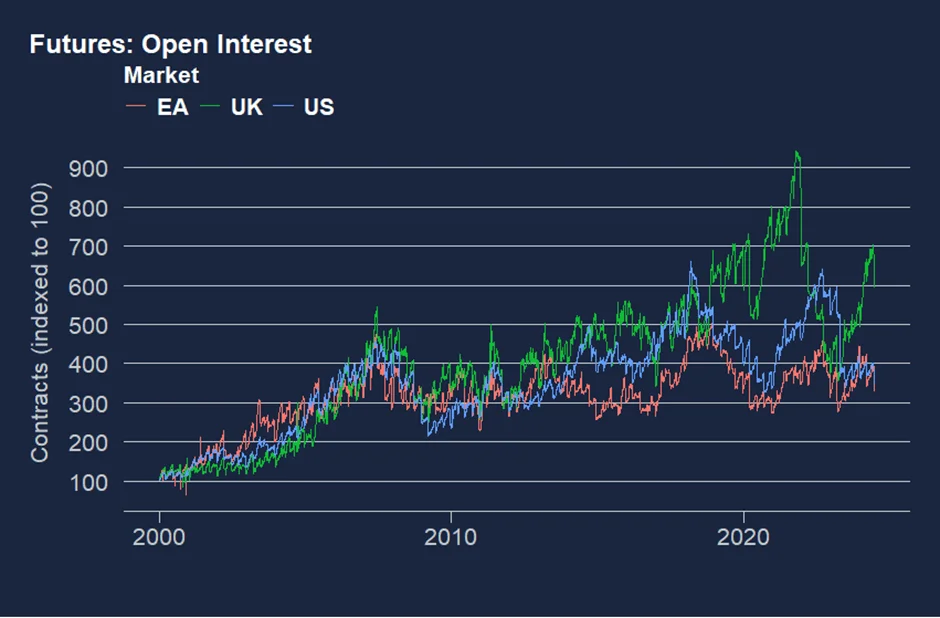
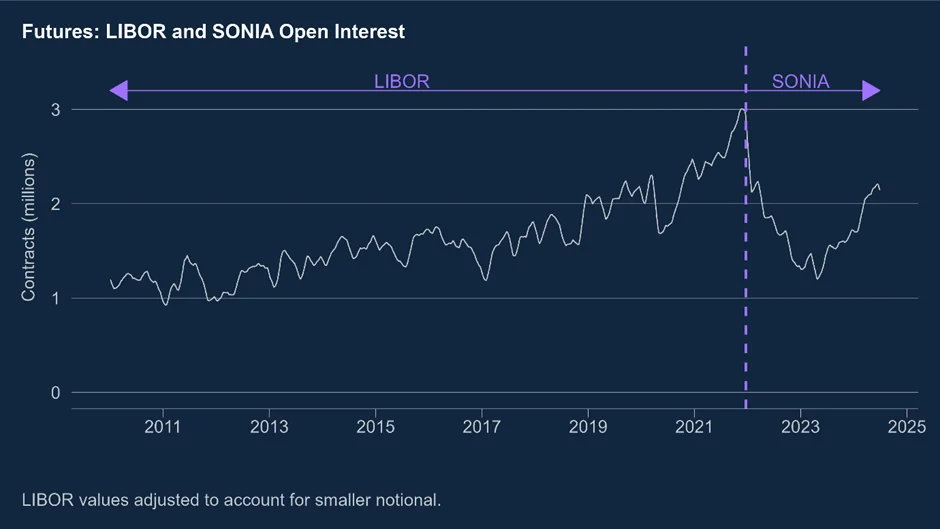
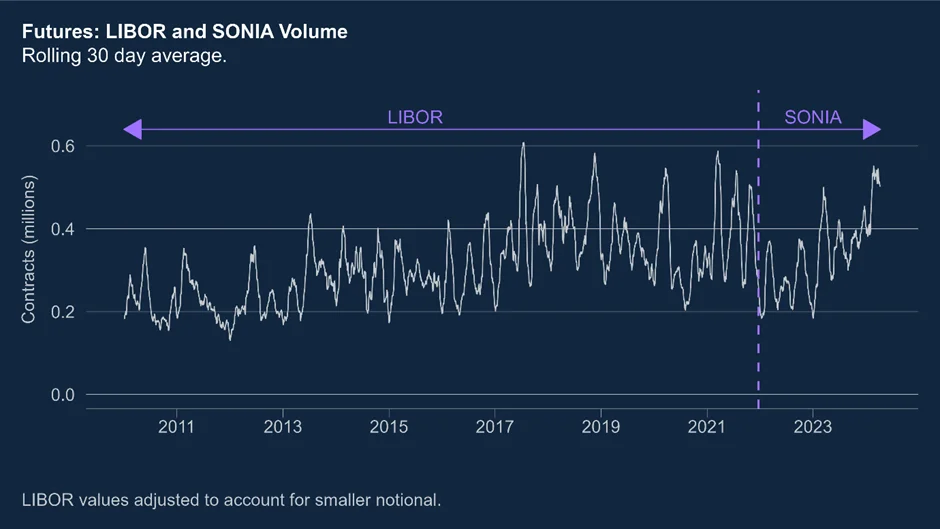
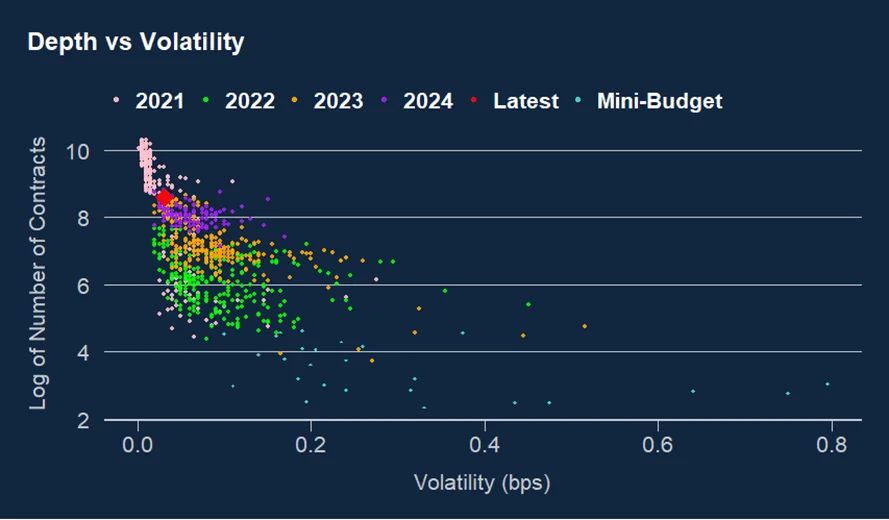
Despite improving headline figures, such as rising open interest and trading volumes nearly comparable to pre-SONIA LIBOR days, deeper liquidity metrics reveal a persistent fragility within the SONIA futures market. Notably, while enhancements in price impact metrics indicate a return toward normalcy post-2022, liquidity remains constrained when adjusted for prevailing volatility. Market depth frequently diminishes during risk events, raising concerns about the durability of current liquidity improvements.
Liquidity and Participation Rates
There remains ongoing apprehension regarding UK risk exposure post-LIBOR transition, as the absence of a credit risk component has impacted the attractiveness of basis trading previously seen in the market. However, signs indicate a resurgence of positive sentiment surrounding SONIA futures, along with various liquidity metrics reflecting this optimism. Assuming volatility remains muted, it is reasonable to anticipate a sustained upward trajectory of liquidity alongside increased confidence and market participation. The cyclic nature of liquidity suggests that when conditions improve, further enhancements often follow.
Data Release Timing and Market Dynamics
A particular point of contention among market participants is the timing of critical UK economic data releases, such as those related to consumer price inflation (CPI) and labor market statistics. Currently set for 07:00 AM, these releases occur when the market is closed, leading to claims that this arrangement contributes to heightened price volatility and lower trading volumes. If key data was released during market operating hours, it could facilitate more effective price discovery and improve overall liquidity by encouraging traditional bank market-makers to engage at these pivotal moments. This timing issue stands in contrast to other jurisdictions, such as the US and Euro Area, where significant data is released amid market hours, contributing to a more dynamic trading environment.
While altering data release times might not single-handedly resolve all underlying issues, it merits consideration as part of a broader effort to foster a healthier ecosystem in the SONIA futures market and its related derivatives.
Conclusion
A deep and liquid SONIA futures market is paramount for the effective transmission of monetary policy and the stability of the UK's financial system. Progress has certainly been made in enhancing liquidity since the extremes of 2022, yet the challenges posed by market fragility and the timing of data releases remain pertinent. Moving forward, a concerted effort toward improving market dynamics and responsiveness may help ensure that the SONIA futures market continues to develop as a reliable cornerstone of the UK interest rate landscape.
David Glanville works in the Bank’s Sterling Markets Division and Arif Merali is a Senior Advisor across the Markets Directorate.
With thanks to Joel Mundy for data and analytics who works in the Bank’s Market Intelligence and Analysis Division.
If you want to get in touch, please email us at [email protected] or leave a comment below.
Comments will only appear once approved by a moderator, and are only published where a full name is supplied. Bank Underground is a blog for Bank of England staff to share views that challenge – or support – prevailing policy orthodoxies. The views expressed here are those of the authors, and are not necessarily those of the Bank of England, or its policy committees.